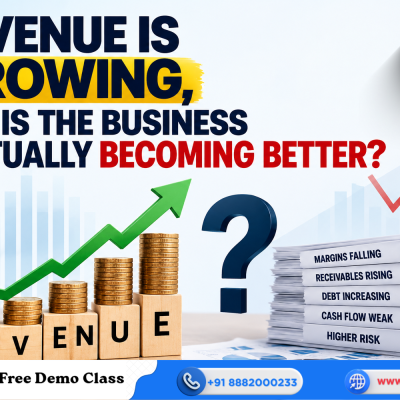
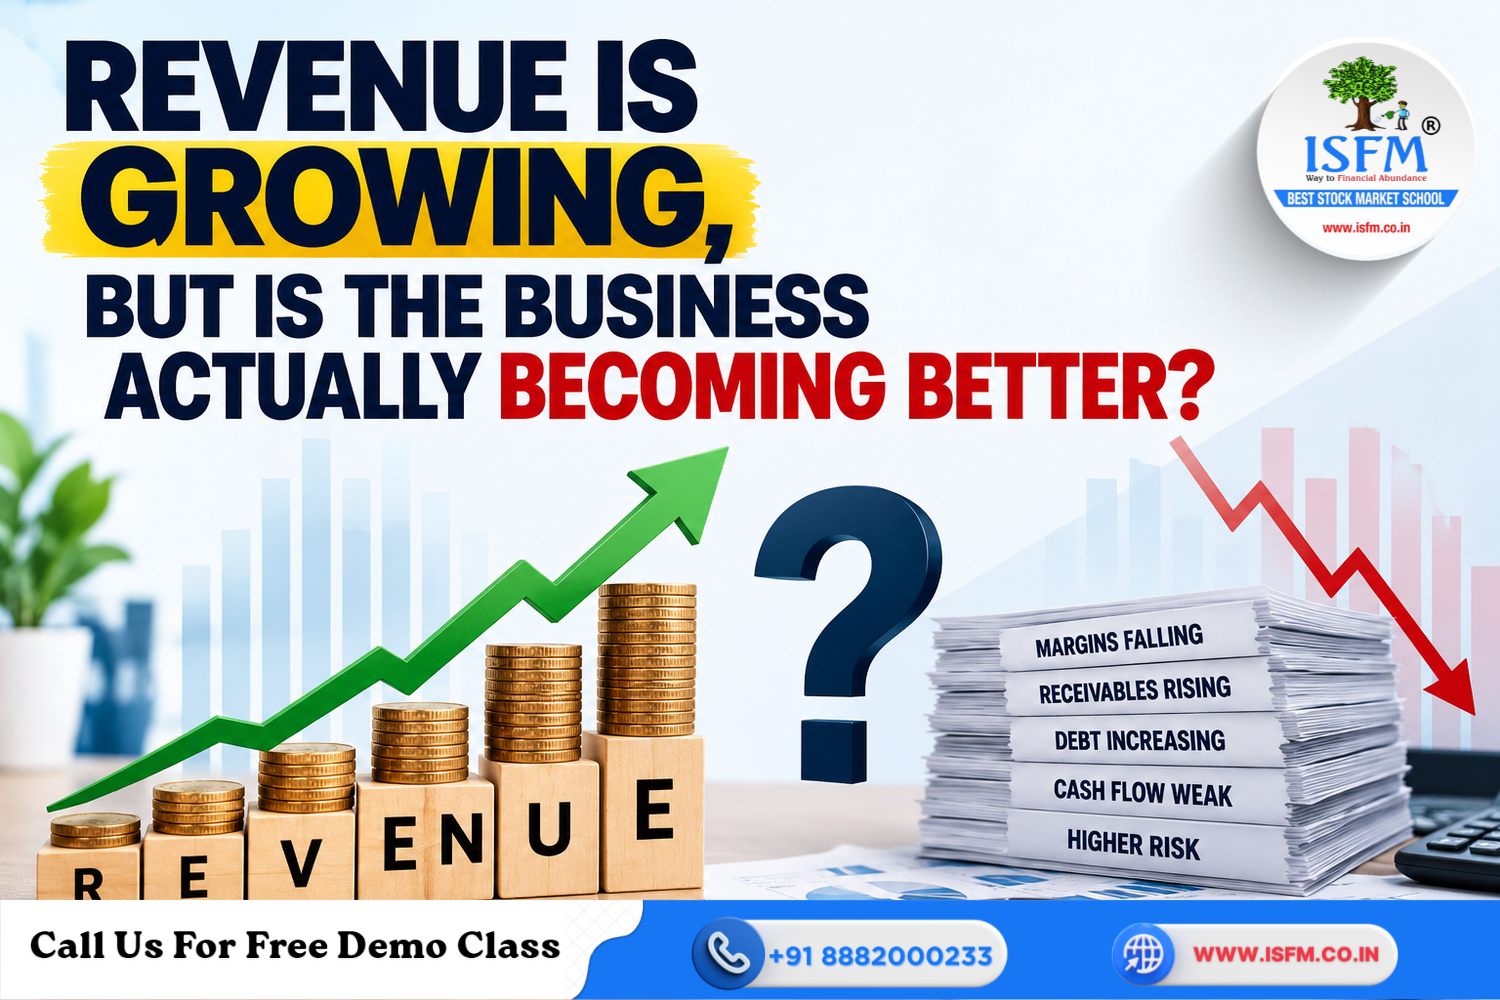
Imagine an NSE-listed company announces 30% revenue growth compared with the previous year. Investors become optimistic, and its stock price starts rising. However, over the next few quarters, operating margins decline, customer payments get delayed, debt increases, and operating cash flow weakens.
The obvious question is: Did the business become better, or did it merely become bigger?
According to Sushil Alewa, SEBI Registered Research Analyst (INH100009433), revenue growth alone should never be the deciding factor when evaluating a company’s financial strength. Investors must examine profitability, cash generation, capital efficiency, and financial risk to understand whether growth is actually creating long-term value.
This is an important principle for anyone learning fundamental analysis and stock market investment.
Revenue Measures Scale, Not Business Quality
Revenue represents the total income generated from selling products or services. It tells investors how much business a company is doing, but not how efficiently it operates.
When analysing quarterly results or annual reports, investors should ask:
- Is the company earning more profit from every sale?
- Are customers actually paying for their purchases?
- Is growth being financed through excessive borrowing?
- Are operating margins improving?
- Is the company using its capital efficiently?
Revenue growth tells you that a company is getting bigger. Business quality tells you whether it is getting better.
Check Gross Margin First
Gross margin measures how much money remains after deducting the direct cost of producing goods or delivering services.
Formula:
Gross Margin = [(Revenue – Cost of Goods Sold) / Revenue] × 100
For example, if a company generates ₹100 crore in revenue and its direct production cost is ₹60 crore, its gross margin is 40%.
A declining gross margin despite rising revenue may indicate increasing raw material costs, competitive pricing pressure, or an unfavourable product mix.
For Indian manufacturing, FMCG, automobile, and consumer companies, this metric helps investors understand pricing power and cost management.
Operating Margin and Net Margin Matter
Gross margin is only the beginning. Investors must also examine:
- Operating Margin: Operating profit as a percentage of revenue, after operating expenses.
- Net Profit Margin: Final profit as a percentage of revenue, after interest, taxes, and other expenses.
If employee, marketing, and administrative costs increase faster than revenue, the company may report higher sales but generate weaker operating profits.
Investors should also check whether net profit growth comes from regular operations or temporary benefits such as asset sales, tax adjustments, and other income.
Stable or improving margins indicate that revenue growth is translating into better profitability. Understanding these financial ratios is an essential part of fundamental analysis training.
Operating Cash Flow: Is Profit Turning Into Cash?
One important principle of fundamental analysis is that profit and cash are not the same.
A company can report increasing profits while struggling to collect payments from customers. Operating cash flow measures the actual cash generated through regular business operations.
Investors should compare operating cash flow with reported profits over several years. If profits consistently increase while operating cash flow remains weak, it deserves further investigation.
Rising inventory, delayed customer payments, and increasing working capital requirements can absorb cash even when accounting profits look healthy.
Receivables and Inventory: Hidden Warning Signs
Two important areas of annual report analysis are trade receivables and inventory.
Receivables represent money customers owe the company. If receivables increase much faster than revenue, the business may be offering excessive credit or experiencing collection difficulties.
Inventory represents goods held for production or sale. If inventory grows faster than revenue, it may indicate excess production, slow-moving products, or weakening demand.
For example, if revenue increases by 25%, but receivables rise by 60% and inventory increases by 50%, investors should investigate the quality of those sales.
These working capital red flags can reveal problems that headline revenue figures often hide.
Return on Capital: Is Growth Worth the Investment?
Return on Capital Employed (ROCE) measures how efficiently a company uses its capital to generate operating profits.
A business requiring substantial additional investment to generate relatively small profits may not be creating meaningful value.
Investors should examine whether ROCE is improving and whether returns on newly invested capital exceed the company’s cost of capital.
Growth funded by large investments is attractive only when those investments generate adequate returns. Otherwise, increasing business size may actually reduce shareholder value.
Debt and Funding Sources Need Attention
Revenue growth can be financed through internal cash generation, equity, debt, or supplier credit.
Borrowing is not necessarily bad. However, investors should be cautious when debt increases faster than earnings and interest expenses grow faster than operating profits.
Frequent fundraising, excessive short-term borrowings, and insufficient operating cash flow to support capital expenditure are additional warning signs.
Understanding derivatives and market risk is another important dimension of investing. Investors interested in expanding their market knowledge can explore ISFM’s Advanced Derivatives Training Course.
Is Management Allocating Capital Wisely?
Management decides whether available cash should be reinvested, used for acquisitions, directed towards debt repayment, or distributed through dividends and buybacks.
Good capital allocation focuses on generating sustainable returns rather than simply increasing revenue.
Investors should examine whether acquisitions create value, expansion projects generate adequate returns, and management uses shareholder capital responsibly.
For those interested in systematic market strategies, ISFM’s Algo Trading Course also introduces the role of technology and data-driven decision-making in financial markets.
A Numerical Example: When 30% Growth Raises Questions
Consider a hypothetical company:
| Financial Metric | Previous Year | Current Year |
| Revenue | ₹1,000 Cr | ₹1,300 Cr |
| Gross Margin | 40% | 30% |
| Operating Margin | 15% | 8% |
| Receivables | ₹200 Cr | ₹400 Cr |
| Operating Cash Flow | ₹120 Cr | ₹40 Cr |
Revenue has increased by 30%, but margins have declined significantly. Receivables have doubled, while operating cash flow has fallen.
The company is selling more but earning less per rupee of sales and struggling to convert business activity into cash. These figures do not automatically prove financial weakness, but they demand deeper investigation.
Questions Investors Should Ask Before Trusting Revenue Growth
Before making a long-term investment decision, examine these questions:
- Is growth coming from higher volumes, pricing, new products, or acquisitions?
- Are gross and operating margins stable?
- Is operating cash flow growing alongside profits?
- Are receivables and inventory under control?
- Is debt increasing faster than earnings?
- Is ROCE improving?
- Is management allocating capital efficiently?
- Can growth continue without excessive discounting or credit expansion?
Reviewing these factors across multiple financial years provides a more reliable picture than looking at a single quarterly result.
Conclusion: Growth Should Create Value, Not Just Size
Revenue growth is an important starting point in fundamental analysis, but it should never be the final measure of a company’s performance.
Investors analysing NSE-listed companies must connect revenue with profitability, operating cash flow, working capital, debt, and return on capital. These indicators help distinguish sustainable business growth from expensive expansion.
A business is not becoming better just because it is selling more. It is becoming better when each additional rupee of revenue creates stronger profits, better cash flow, and more durable value.
Disclaimer: This article is intended for educational purposes only and does not constitute investment advice or a recommendation to buy or sell any security. Investors should conduct independent research and assess their financial risk before making investment decisions.