Blog

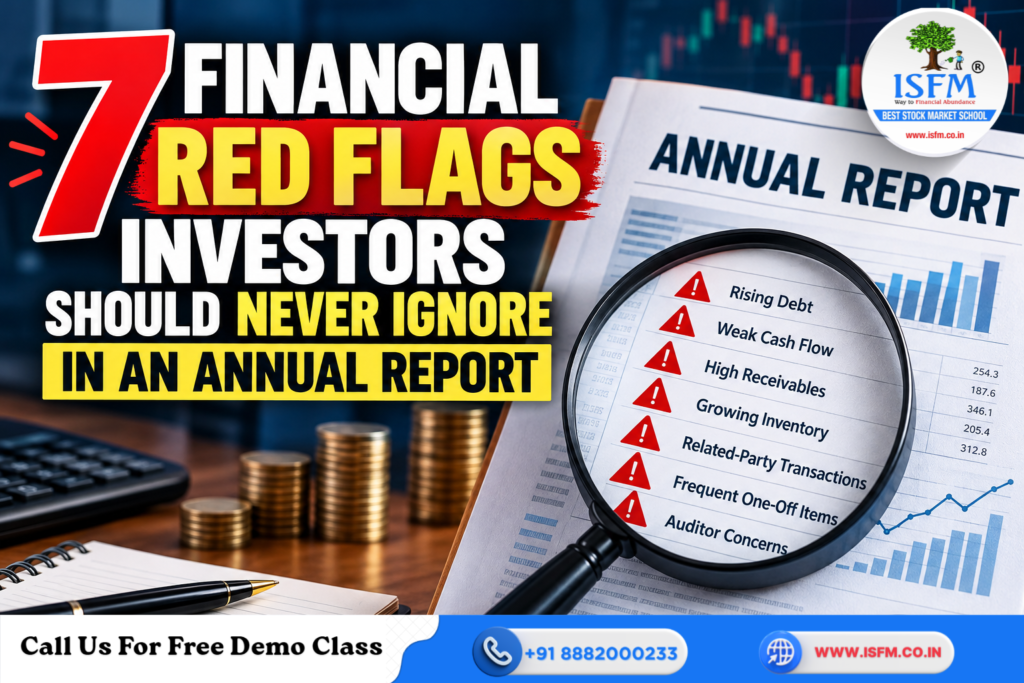
7 Financial Red Flags Investors Should Never Ignore in an Annual Report
Blog

7 Financial Red Flags Investors Should Never Ignore in an Annual Report

A company’s share price may rise because of positive news, market sentiment, or strong quarterly results. However, its annual report reveals deeper insights into profitability, debt, cash flow, and corporate governance. For investors analysing NSE-listed companies, understanding annual report red flags is essential for effective fundamental analysis. According to Sushil Alewa, SEBI Registered Research Analyst (INH100009433), investors should look beyond reported profits and examine the financial patterns that reveal a company’s actual business performance. An annual report should be analysed through its income statement, balance sheet, cash-flow statement, notes to accounts, and auditor’s report. A red flag does not prove fraud or business failure. It signals the need for further investigation. 1. Profit Without Cash Flow Reported profit is not the same as cash received. A company may report rising net profit while generating weak or negative operating cash flow because customers delay payments or working-capital requirements increase. Compare operating cash flow with net profit over five years. A persistent gap may indicate weaker earnings quality and deserves investigation. To understand financial statement analysis in greater depth, explore ISFM’s Fundamental Analysis Course. 2. Receivables Growing Faster Than Revenue Trade receivables represent money customers owe for goods or services already supplied. For example, if revenue rises 20% but receivables increase 60%, collections may be slowing or credit sales may be growing disproportionately. Rising debtor days and provisions for doubtful debts deserve attention. Compare receivables growth, revenue growth, and collection periods before drawing conclusions. 3. Inventory Building Faster Than Sales Inventory includes raw materials, work-in-progress, and finished goods. Rapid inventory growth alongside sluggish sales may indicate weakening demand, inefficient production, or unsold products. Declining inventory turnover and repeated stock write-downs are additional warning signs. However, seasonal demand and planned expansion can also explain higher inventory. 4. Rising Debt and Weak Repayment Capacity Borrowing can support expansion, but excessive debt becomes risky when cash generation cannot cover interest and repayments. Examine total borrowings, short-term liabilities, interest coverage, debt-to-equity, and upcoming maturities. Significant repayments within twelve months, combined with limited cash, may create liquidity pressure. Assess whether borrowing finances productive growth or recurring operating losses. Investors interested in market behaviour can also explore ISFM’s Technical Analysis Course. 5. Frequent “One-Off” Items Exceptional expenses, restructuring charges, and asset impairments can legitimately occur. However, repeated supposedly exceptional losses may indicate persistent operational problems. Similarly, profits heavily dependent on asset sales or other income may overstate the strength of core operations. Compare operating profit and exceptional items across several years. 6. Related-Party Transactions These transactions involve promoters, directors, subsidiaries, associates, or connected entities. They may be legitimate, but large loans, unclear pricing, persistent outstanding balances, or transactions lacking commercial justification deserve scrutiny. Read the notes to accounts to understand transaction values, business purposes, repayment terms, and outstanding balances. 7. Auditor Concerns and Accounting Changes The auditor’s report provides an independent opinion on whether financial statements present a true and fair view under applicable accounting standards. Warning signs include qualified or adverse opinions, auditor resignations, going-concern concerns, restated financial statements, and frequent accounting-policy changes. Investigate material qualifications and explanations rather than assuming misconduct. How to Investigate Financial Red Flags Before making an investment decision: Investors seeking to understand derivatives and market risk can explore ISFM’s Options Trading Course or Advanced Derivatives Course. Those interested in systematic market strategies may also consider the Algo Trading Course. Frequently Asked Questions 1. What are financial red flags in an annual report? They are warning signs of potential financial weakness, poor earnings quality, or governance concerns. 2. Is rising debt always bad? No. Debt can finance growth, but inadequate cash flow to service it increases risk. 3. Do auditor qualifications prove fraud? No. They identify concerns that investors should investigate further. 4. How should investors investigate a red flag? Compare historical performance, industry peers, financial disclosures, and management explanations before deciding. Conclusion Annual reports reveal how companies earn, spend, borrow, and manage risks. Careful analysis helps investors make more informed decisions. “A red flag does not tell you to sell immediately. It tells you to slow down, investigate the pattern, and understand whether the business is facing a temporary problem or a structural weakness.” Disclaimer: This article is for educational purposes only and is not investment advice or a recommendation to buy or sell securities. Conduct independent research before making investment decisions.
FOMO in Trading:
Blog

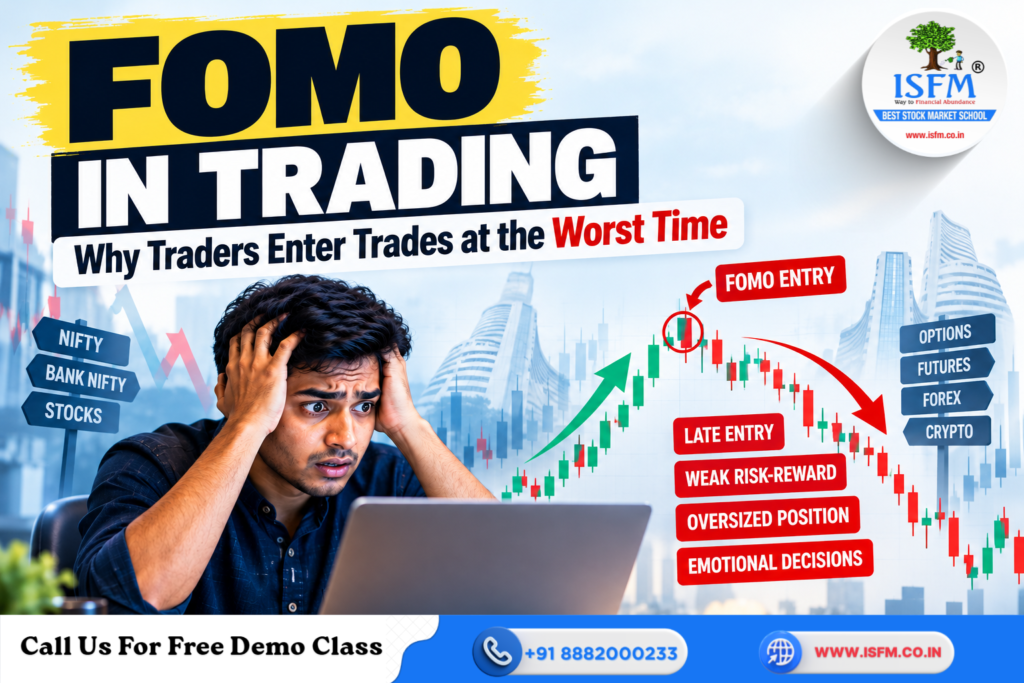
FOMO in Trading: Why Traders Enter Trades at the Worst Time?

Imagine watching a stock break above resistance. You wait for confirmation, but the price keeps rising. Another strong green candle appears, and you fear missing the opportunity. Finally, you enter near the top. Minutes later, the stock pulls back and hits your stop-loss. According to Sushil Alewa, SEBI Registered Research Analyst (INH100009433), understanding FOMO in trading helps traders recognise how emotional reactions can lead to late entries, unfavourable risk-reward ratios, oversized positions, and impulsive decisions. However, avoiding FOMO does not guarantee profitable trades, as market volatility, entry timing, liquidity, and risk management also influence trading outcomes. Why did the trader enter exactly when the probability of profit was lowest? This is a common example of FOMO in trading. Instead of following a predefined plan, the trader allows the fear of missing a move to control the decision. What Is FOMO in Trading? FOMO, or fear of missing out, is the anxiety traders experience when they believe they are about to miss a profitable opportunity. It often occurs during rapid price movements, strong breakouts, major news events, or when social media highlights someone else’s winning trade. Indian traders may experience FOMO while trading equities, Nifty, Bank Nifty, futures, options, forex, or cryptocurrencies. A losing streak can intensify this feeling because traders may try to recover losses quickly. FOMO is an emotional reaction rather than a calculated decision. It compresses analysis time and encourages traders to enter before checking whether a setup meets their trading rules. Why FOMO Leads to Late Entries? Traders often hesitate when a move begins because they want confirmation. However, as the price continues rising, their fear of missing out becomes stronger than their original caution. They eventually enter after an extended candle, when much of the immediate price movement may already have occurred. The market can then experience profit-booking, a pullback, or a false breakout. Consider a stock trading near ₹500 that breaks above resistance at ₹505. A trader waits, but the price reaches ₹520. Fearing that the rally will continue without them, the trader buys at ₹520. If the stock falls to ₹512, the trader faces an ₹8-per-share loss before costs. The original breakout may have been genuine, but the late entry created an unfavourable risk-reward situation. Learning to identify price structure and confirmation through ISFM’s Technical Analysis Course can help traders develop a more systematic approach to evaluating potential entries. The Psychology Behind FOMO A rapidly moving market makes recent candles appear more important than the broader price structure. Traders begin assuming that a rising price will continue rising. Missing a rally can also feel like losing money, even though no actual financial loss has occurred. This creates urgency to participate at almost any price. How FOMO Damages Risk-Reward Late entries can create several problems: Even a correct market prediction can produce a poor trade when the entry price and risk parameters are unfavourable. ISFM’s Options Trading Course can help learners understand how timing, volatility, and option pricing affect trading risk. Common FOMO Situations in Indian Markets FOMO can appear when traders chase a large breakout candle in Nifty, buy Bank Nifty options after a sudden spike, or enter futures following a news-driven rally without assessing follow-through. Others buy trending stocks because an influencer recommends them or jump into an extended cryptocurrency rally after seeing impressive returns posted online. After a losing streak, traders may take additional trades to recover their losses. They ignore confirmation, abandon position-sizing rules, and chase breakouts without considering the potential downside. However, not every breakout entry is a FOMO trade. A planned entry that satisfies predefined conditions is different from an impulsive decision driven by urgency. FOMO and Overtrading FOMO can turn one missed opportunity into a series of unnecessary trades. A trader misses a breakout, enters the next move impulsively, suffers a loss, and immediately searches for another trade to recover. This cycle increases transaction costs and can lead to excessive exposure in the same direction. Learning structured trade management through ISFM’s Advanced Derivatives Course can help traders better understand derivatives risk. Meanwhile, the Algo Trading Course introduces learners to rule-based execution and systematic testing. Neither approach eliminates market risk or guarantees better results. How to Recognise and Avoid FOMO Trades Watch for these warning signs before placing an order: To reduce FOMO, define entry conditions before the session, avoid chasing extended moves, set daily trade limits, and take a break after missing an opportunity. Maintain a trading journal to identify recurring emotional mistakes. ISFM’s Fundamental Analysis Course can also help investors evaluate businesses using financial information rather than relying solely on market excitement. What to Do After Missing a Trade Accept that missing trades is normal. Record the opportunity, identify why you did not enter, and check whether the setup actually met your rules. If the setup was unclear, waiting may have been the correct decision. If it was valid but you hesitated, review the decision after the session rather than chasing the price. Wait for the next valid opportunity instead of forcing a replacement trade. Your goal is not to catch every market movement but to follow a repeatable process. Conclusion FOMO is dangerous because impulsive decisions can feel rational in the moment. A rapidly rising market creates urgency, but urgency is not evidence of a good entry. The best defence against FOMO is not a better indicator. It is a clear plan, predefined entries, and the willingness to let a move pass if it does not meet your rules. Financial Risk Disclaimer: Trading in equities, futures, options, forex, and cryptocurrencies involves significant risk. Leverage can magnify losses. This article is for educational purposes only and does not constitute investment advice or a recommendation to buy or sell any financial instrument. Frequently Asked Questions (FAQs) What does FOMO mean in trading? FOMO means fear of missing out. It occurs when traders enter a market impulsively because they fear losing a potential profit opportunity. Why do traders enter trades late? Traders often wait for confirmation and then

NISM Series X-A vs X-B:
Blog

NISM Series X-A vs X-B: Which Investment Adviser Level Should You Take First?

If you are planning a career in investment advisory, financial planning or wealth management, the NISM Investment Adviser certifications are among the most important qualifications to understand. But one common question confuses many aspirants: Should I take NISM Series X-A first, or can I start directly with X-B? The answer is straightforward: NISM Series X-A is Level 1 and should be your starting point, followed by NISM Series X-B (Level 2). For individuals and associated persons covered by the applicable investment-adviser certification requirements, both levels are required rather than being alternative certifications. This guide explains the NISM Series X-A vs X-B syllabus, exam pattern, difficulty, career relevance, preparation strategy and the right order to take both examinations. What Are NISM Series X-A and X-B? The National Institute of Securities Markets (NISM) conducts two certification examinations specifically for the Investment Adviser function: NISM describes X-A as Level 1 and X-B as Level 2. An individual investment adviser or principal officer of a non-individual investment adviser, as well as relevant persons associated with investment advice, may be required to pass both examinations to satisfy the applicable certification requirements. So, these exams should not be viewed as “X-A vs X-B” in the sense of choosing one permanently. Instead, think of them as: X-A → Foundation → X-B → Advanced Investment Advisory Knowledge NISM X-A vs X-B: Quick Comparison Parameter NISM Series X-A NISM Series X-B Level Level 1 Level 2 Full Name Investment Adviser (Level 1) Investment Adviser (Level 2) Recommended Order First Second Main Focus Financial planning, investments, markets & advisory fundamentals Insurance, retirement, taxation, estate planning, behavioral finance & risk profiling Exam Duration 3 hours 3 hours Total Marks 150 150 Passing Score 60% 60% Negative Marking 25% 25% Exam Format MCQs + case-based questions MCQs + caselets Current Listed Fee ₹3,000 ₹3,000 Best For Building fundamental advisory knowledge Developing advanced advisory knowledge Should Beginners Start Here? Yes Generally no NISM’s current certification listing shows both X-A and X-B with a ₹3,000 examination fee, 150 marks, 60% passing requirement, 25% negative marking and a three-hour duration. What Is NISM Series X-A? NISM Series X-A: Investment Adviser (Level 1) is the foundation-level certification. It is designed to establish fundamental knowledge required for investment advisory and financial planning. The syllabus covers areas such as financial planning, investment returns, risk, investment products, portfolio construction, asset allocation and related advisory concepts. Major Topics Covered in X-A Some important areas include: 1. Personal Financial Planning You learn how financial planning works in practical situations, including: 2. Time Value of Money This is an important numerical component. You may need to understand concepts such as: These concepts are particularly useful when constructing financial plans for clients. 3. Investment Products X-A introduces candidates to different investment vehicles, including: 4. Risk and Portfolio Management Candidates also learn about: The objective is not simply to understand individual products but to understand how investments can fit into a client’s overall financial plan. What Is NISM Series X-B? NISM Series X-B: Investment Adviser (Level 2) builds on the knowledge developed through Level 1. Its focus is more closely connected to advanced areas of comprehensive financial advice. NISM identifies areas including insurance planning, retirement products, estate planning, taxation, behavioral finance and risk profiling among the examination objectives. Major Topics Covered in X-B 1. Insurance Planning The candidate develops knowledge about: 2. Retirement Planning Retirement planning is another important component. The candidate needs to understand retirement products and their features and the role of an Investment Adviser in retirement planning. 3. Estate Planning This section deals with concepts surrounding: 4. Taxation Candidates need to understand the taxation aspects associated with different financial securities and investment decisions. 5. Behavioral Finance This is particularly important from a real-world advisory perspective. An investor may have sufficient money and access to good financial products but still make poor decisions because of: Understanding behavioral finance helps advisers appreciate why clients sometimes behave differently from what traditional financial models assume. NISM X-A vs X-B: Which Is More Difficult? There is no universal answer because difficulty depends on your educational and professional background. However, X-B generally feels more advanced because it expects candidates to apply knowledge across different areas of financial planning and advisory. X-A can feel difficult if you are weak in: X-B can feel difficult if you are weak in: The biggest mistake is assuming that X-B is simply a second independent examination that can be prepared for without understanding X-A. NISM X-A Exam Pattern According to NISM’s current information, the X-A examination consists of 90 independent MCQs and 9 caselets/case-based questions, carrying a total of 150 marks. The examination duration is 3 hours, the passing score is 60% (90/150) and there is 25% negative marking for an incorrect answer. X-A at a Glance This means candidates should avoid blind guessing, particularly when they are uncertain between multiple options. NISM X-B Exam Pattern The X-B examination also carries 150 marks and has a three-hour duration. NISM specifies: The caselets make application-based preparation particularly important. Can You Take X-B Before X-A? This is where candidates often get confused. NISM’s FAQ indicates that interested students, professionals and other individuals can take the X-B examination. However, for fulfilling the applicable Investment Adviser certification requirement, both X-A and X-B are required. Therefore, even though someone may technically be eligible to register for X-B, X-A → X-B remains the logical learning sequence. Why? Because X-A establishes the foundation required to understand: Client → Goals → Risk Profile → Investment Products → Asset Allocation → Portfolio → Monitoring X-B then expands this into more comprehensive financial planning areas. Which One Should You Take First? The answer: NISM Series X-A If you are starting your Investment Adviser certification journey, take NISM Series X-A first. A recommended sequence is: Step 1: Study NISM Series X-A↓Step 2: Pass X-A↓Step 3: Prepare for X-B↓Step 4: Pass X-B↓Step 5: Understand the applicable SEBI qualification and registration requirements before offering investment advice This sequence creates a more structured learning path.

Larry Williams Success Story
Blog

Larry Williams Success Story: The Trader Who Turned Market Research Into a Trading Legacy

In 1987, American futures trader Larry Williams reportedly transformed an account of $10,000 into approximately $1.137 million in just twelve months during the World Cup Trading Championship. His remarkable performance, often quoted as a return of approximately 11,376%, made him one of the most recognised names in trading history. However, such extraordinary returns involve significant risk and should not be considered realistic expectations for ordinary traders. According to Sushil Alewa, SEBI Registered Research Analyst (INH100009433), Larry Williams’ journey highlights an important lesson for traders: understanding market behaviour, developing systematic rules, and managing risk are more valuable than chasing extraordinary returns without a clear strategy. Early Interest in Financial Markets Larry Williams began following financial markets in 1962. His curiosity about price movements gradually developed into a career involving futures trading, market research, writing, and financial education. Rather than relying entirely on intuition, Williams explored how prices behaved under different market conditions. He studied stocks, commodities, and futures to identify patterns that could help traders make informed decisions. His ability to communicate complex market concepts also contributed to his reputation. Through books, articles, and educational programmes, he shared his observations with traders worldwide. One of his most recognised contributions was the development of the Williams %R indicator in 1966, which remains a popular technical analysis tool. From Market Observation to Systematic Trading Williams’ approach focused on understanding the factors that influence market movements. His research covered price patterns, market cycles, seasonal tendencies, volatility breakouts, and futures positioning. He also examined open interest, which represents outstanding futures or options contracts, to understand participation in derivatives markets. Such information can provide additional context when combined with price movements. His approach illustrates the value of systematic trading. Traders define their entry conditions, exit rules, and risk limits before placing a trade rather than making every decision emotionally. However, having a systematic strategy does not guarantee profits. Market conditions change, and even well-researched strategies experience losing trades. The objective is to make decisions consistently and evaluate performance using evidence rather than assumptions. Traders interested in understanding price patterns, momentum, and market trends can explore ISFM’s Technical Analysis Course to develop a structured foundation in chart analysis. The Famous World Cup Trading Championship Williams’ performance in the 1987 World Cup Trading Championship remains the most celebrated achievement of his career. He reportedly started with $10,000 and finished the competition with approximately $1.137 million over twelve months. The result is frequently described as a return of around 11,376%, although published accounts sometimes round the figure differently. This historical achievement demonstrates what was possible in a particular trading competition, not what traders should expect to earn consistently. Futures contracts involve leverage, which magnifies both profits and losses. A spectacular result in one year does not establish a sustainable long-term return, and attempting to reproduce it can expose traders to severe financial losses. Understanding the Williams %R Indicator The Williams %R indicator is a momentum oscillator that compares the latest closing price with the highest and lowest prices over a selected period. It generally moves between zero and minus one hundred. Readings closer to zero indicate that the price is near the top of its recent range, while readings closer to minus one hundred indicate that it is near the bottom. Readings above minus twenty are commonly considered overbought, while readings below minus eighty are often considered oversold. However, these readings do not automatically predict reversals. A strongly rising market can remain overbought, while a falling market can remain oversold for an extended period. Traders should interpret Williams %R alongside the prevailing trend, volatility, support and resistance, and other relevant market information instead of relying on it as a standalone trading signal. Developing these skills through technical analysis training can help learners understand indicators in their broader market context. Market Timing and Research Williams’ work demonstrates the importance of examining several market conditions together. Seasonality helps identify recurring historical tendencies in particular markets. Commitment of Traders reports provide information about futures positioning, while open interest offers insights into participation. Cycle analysis examines recurring patterns, and price action helps traders evaluate changing market conditions. Combining these sources can improve the quality of market analysis. Nevertheless, historical patterns are not guarantees, and positioning data cannot reliably predict every future price movement. Understanding economic conditions can also complement technical research. Learners interested in examining company performance, economic indicators, and broader market influences can explore ISFM’s Fundamental Analysis Course. The key is to use research to develop informed probabilities rather than assume certainty. Risk Management: The Other Side of Trading Success Many traders focus on profits while overlooking the risks required to achieve them. Effective risk management considers position size, leverage, transaction costs, potential drawdowns, and the possibility of consecutive losing trades. For example, if a trader loses fifty per cent of an account worth ₹1,00,000, the remaining capital is ₹50,000. Recovering the original amount requires a one-hundred-per-cent gain on the remaining capital. This illustrates why protecting trading capital is essential. Traders should establish risk limits, maintain performance records, and avoid increasing exposure simply because they want to recover previous losses. Before trading derivatives, it is important to understand how options work, how their prices change, and how losses can accumulate. ISFM’s Options Trading Course is relevant for learners seeking to build their understanding of options and derivatives. Lessons for Modern Traders Larry Williams’ career offers several valuable lessons. Study market behaviour carefully, convert observations into testable rules, maintain a trading journal, and evaluate strategies using realistic assumptions about costs and execution. Avoid depending on a single indicator or copying another trader’s position sizes and leverage. A method developed by an experienced futures trader may not suit someone trading Indian equity or index options. Traders interested in converting predefined rules into automated strategies can explore ISFM’s Algo Trading Course to learn about systematic trading approaches. Continuous learning, disciplined execution, and realistic expectations remain essential for long-term improvement. Conclusion Larry Williams’ success story is about more than an extraordinary trading-contest return. It demonstrates

How to Identify Liquidity Zones on a Stock Chart
Blog

How to Identify Liquidity Zones on a Stock Chart?

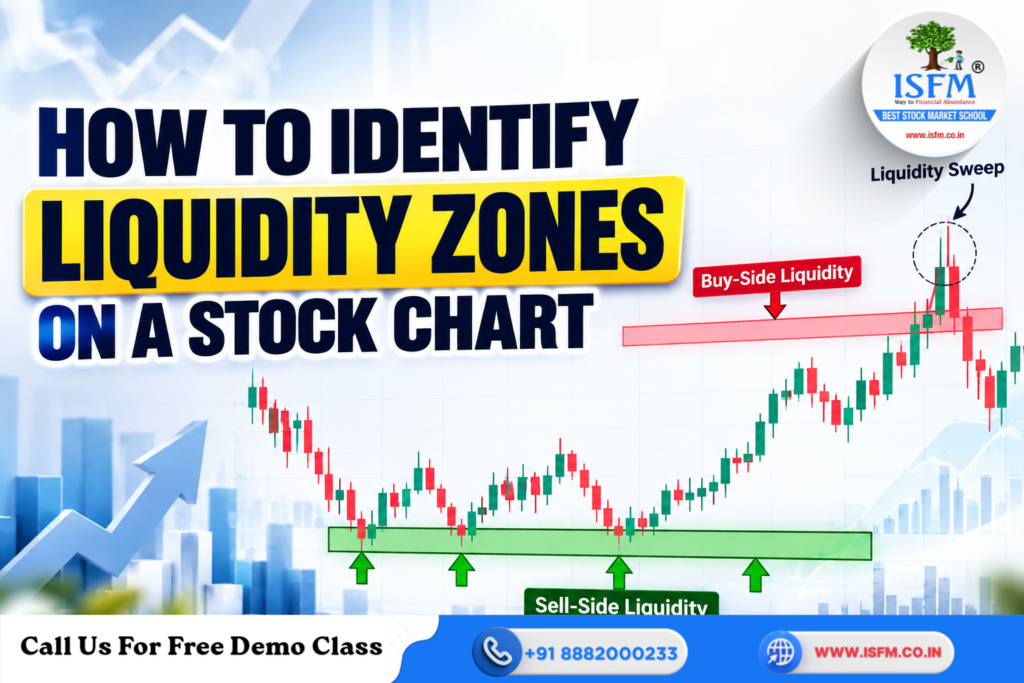
A stock trades repeatedly near ₹500 and forms two similar highs around ₹510. Traders may place stop-losses above ₹510, while breakout traders may prepare to buy above this level. If the stock rises to ₹512 and then falls below ₹510, traders may describe the move as a liquidity sweep. According to Sushil Alewa, SEBI Registered Research Analyst (INH100009433), liquidity analysis helps traders identify important price areas where orders may be concentrated and observe whether the market rejects or accepts those levels. However, these zones are estimates, not proof of institutional activity. Understanding liquidity zones on stock charts helps traders identify important price areas and observe potential market reactions. However, these zones are estimates, not confirmed locations of institutional orders. What Is a Liquidity Zone? A liquidity zone is an estimated price area where buy orders, sell orders, stop-losses, and pending entry orders may cluster. A normal candlestick chart cannot reveal the identity or complete positions of market participants. Traders use price action, volume, and market structure to estimate these areas. Learning to read these patterns is an important part of Technical Analysis Course, which helps traders understand price behaviour and chart patterns. Buy-Side and Sell-Side Liquidity Buy-side liquidity is commonly estimated above recent highs, equal highs, and resistance levels. Short sellers may have stop-loss buy orders above these areas, alongside breakout buy orders. Sell-side liquidity is commonly estimated below recent lows, equal lows, and support levels, where long traders’ stop-loss orders may cluster. For example, if an NSE stock forms equal highs near ₹1,000 and equal lows near ₹960, traders may watch above ₹1,000 for potential buy-side liquidity and below ₹960 for potential sell-side liquidity. Neither level guarantees a reversal. How to Identify Liquidity Zones on Stock Charts Traders interested in Advanced Derivatives Course can apply these concepts to understanding price levels in futures and options markets. Use Volume to Support Your Analysis Volume helps identify areas of concentrated trading activity. Volume Profile highlights high-volume nodes, where substantial trading occurred, and low-volume areas with comparatively less activity. A volume spike during a breakout may indicate increased participation. However, volume alone cannot prove institutional buying or selling. Bid-ask spreads, market depth, turnover, and price impact also influence market liquidity. For a broader understanding of market behaviour, Fundamental Analysis Course can complement chart-based analysis by helping traders evaluate a company’s financial position and business fundamentals. Liquidity Sweep vs Genuine Breakout A liquidity sweep occurs when price briefly moves beyond an obvious high or low and then returns inside the previous range. For example, Bank Nifty may cross a previous session high but quickly fall below it. This could indicate a failed breakout. Conversely, a strong close beyond the level, followed by continued movement, may suggest a genuine breakout. Feature Possible liquidity sweep Possible genuine breakout Price action Brief move beyond a level Strong close beyond a level Follow-through Quickly reverses Continues moving Retest Returns inside the range Broken level may hold Volume Spike followed by rejection Sustained activity may support continuation No single feature confirms either outcome. Wicks can result from ordinary volatility, changing demand and supply, or order execution—not necessarily manipulation. A Practical Trading Checklist For options traders, remember that underlying price movements do not determine premiums alone. Implied volatility, time to expiry, and other factors also matter. The Options Trading Course can help learners explore option strategies and risk management. Frequently Asked Questions 1. How do you identify liquidity zones? Look for previous highs and lows, equal highs and lows, range boundaries, round numbers, and areas of significant trading activity. 2. What is buy-side liquidity? It is a potential concentration of orders above visible highs, including short sellers’ stop-losses and breakout buy orders. 3. What is a liquidity sweep? It is a brief move beyond an obvious price level followed by a return inside the previous range. 4. Can liquidity zones predict reversals? No. They highlight areas to monitor, but price may reverse, consolidate, or continue through them. Conclusion Liquidity zones help traders organise charts around potential order concentrations and price reactions. Use them alongside market structure, volume, and confirmation—not as standalone entry signals. Disclaimer: This article is for educational purposes only and is not investment advice. Stock, futures, and options trading involve financial risk and may result in substantial losses.

Can a Great Company Be a Bad Investment
Blog

Can a Great Company Be a Bad Investment?

Can a company with excellent management, strong brands, and consistent profits still be a poor investment? Yes. Even the best businesses can deliver disappointing stock market returns when investors pay too much for their shares. In the Indian stock market, investors often look for companies with strong fundamentals and reliable earnings. However, buying a great business does not automatically mean buying a great stock. According to Sushil Alewa, SEBI Registered Research Analyst (INH100009433), understanding the relationship between business quality, valuation, and market expectations is essential for making informed investment decisions. A financially strong company may still deliver disappointing returns if investors pay an excessive price for its shares. Evaluating fundamentals alongside valuation helps investors assess potential returns and avoid overpaying for quality. A good company is about the business. A good investment is about the relationship between the business, the price, and the expectations already built into that price. What Makes a Company Great? A great company typically has sustainable competitive advantages, consistent revenue growth, healthy cash flows, capable management, and manageable debt. Strong brands, customer loyalty, pricing power, and high returns on invested capital can also indicate business quality. For example, an established Indian consumer goods company may benefit from a strong distribution network and repeat purchases, helping it maintain profitability during economic slowdowns. Investors can strengthen their understanding of financial statements through ISFM’s Fundamental Analysis Course, which covers the financial and business factors used to evaluate companies. However, these qualities do not guarantee attractive shareholder returns at every price. Business quality and investment attractiveness are related, but they are not identical. What Makes an Investment Good? A good investment depends on the price paid, future earnings potential, business risks, and the investor’s time horizon. Suppose two companies operate in the same sector. One trades at a P/E ratio of 25, while another trades at 65. The second company may have stronger growth prospects, but its valuation also reflects higher expectations. Investors must consider intrinsic value, future earnings, financial risks, and alternative opportunities. Even when profits increase, a stock can deliver weak returns if its starting valuation is excessive. Learning how to interpret price movements alongside business fundamentals can complement this process. ISFM’s Technical Analysis Course introduces chart-based methods for studying price trends and market behaviour. Why Valuation Matters? Valuation compares a company’s market price with its earnings, assets, cash flows, or estimated intrinsic worth. Common valuation measures include the P/E ratio, price-to-book ratio (P/B), EV/EBITDA, and free-cash-flow yield. A high P/E ratio often reflects expectations of substantial future growth. A low P/E ratio may indicate an undervalued opportunity, but it could also signal weak earnings prospects or serious business risks. Understanding valuation vs quality is essential because overpaying for quality stocks can reduce future returns, even when the underlying business performs well. When Expectations Are Already Priced In? Stock prices reflect investors’ collective expectations about a company’s future. When an NSE-listed company trades at a premium valuation, the market may already anticipate years of strong earnings growth. If the company meets those expectations without exceeding them, its share price may rise only modestly or remain stagnant. If growth slows unexpectedly, investors may assign the business a lower valuation multiple, causing the stock to fall. A company can execute well and still disappoint investors if it fails to exceed already-high expectations. Investors who want to understand how derivatives markets reflect expectations and risk can explore ISFM’s Advance Derivatives Course, which covers concepts relevant to derivatives analysis and trading. A Simple Numerical Example Consider Company A, which earns ₹10 per share and trades at a P/E ratio of 60. Its share price is: ₹10 × 60 = ₹600 Over the next three years, earnings grow by 50%, reaching ₹15 per share. However, the market becomes less optimistic and values the company at a P/E ratio of 35. The new share price becomes: ₹15 × 35 = ₹525 Despite 50% earnings growth, an investor who purchased the stock at ₹600 faces a price decline of ₹75, or 12.5%, excluding dividends. This example demonstrates how earnings growth and valuation changes interact. A great business can become a poor investment when the initial purchase price assumes too much. Lessons from Indian Market Patterns Indian equity markets have experienced periods when popular consumer, FMCG, and technology stocks commanded premium valuations. When expectations became difficult to sustain, some stocks delivered muted returns despite continued business growth. Similarly, cyclical companies can deliver strong returns when purchased at depressed valuations and their earnings subsequently recover. However, a low valuation alone does not make a stock attractive; the business must remain financially viable. For Nifty investors, this distinction matters because companies within the same index or sector can have very different valuations, growth expectations, and risk profiles. Investors interested in systematic strategies can also explore ISFM’s Algo Trading Course to learn about rule-based trading approaches and strategy evaluation. Algorithmic methods, however, do not eliminate valuation risk or guarantee returns. Why Great Companies Become Expensive Successful businesses attract attention. Strong historical performance builds confidence, analysts project continued growth, and media coverage increases investor interest. Investors may then assume that past growth will continue indefinitely. The reputation of a high-quality company can itself command a premium. When optimism becomes excessive, even respectable earnings growth may not justify the share price. Future returns can suffer because the market has already priced in much of the company’s potential. The Importance of a Margin of Safety A margin of safety means purchasing an investment below a conservative estimate of its intrinsic value. This approach allows room for slower growth, unexpected costs, competitive pressure, and errors in valuation assumptions. For example, if an investor estimates a company’s intrinsic value at ₹500 per share, purchasing it at ₹400 provides a potential valuation cushion. However, the estimate could still be wrong, and the investment can lose value. A margin of safety reduces dependence on optimistic assumptions; it does not guarantee profits. Can a Mediocre Company Be a Good Investment? Sometimes, yes. An average business trading

The Psychology of a Losing Trade
Blog

The Psychology of a Losing Trade: What Happens Inside a Trader’s Mind?

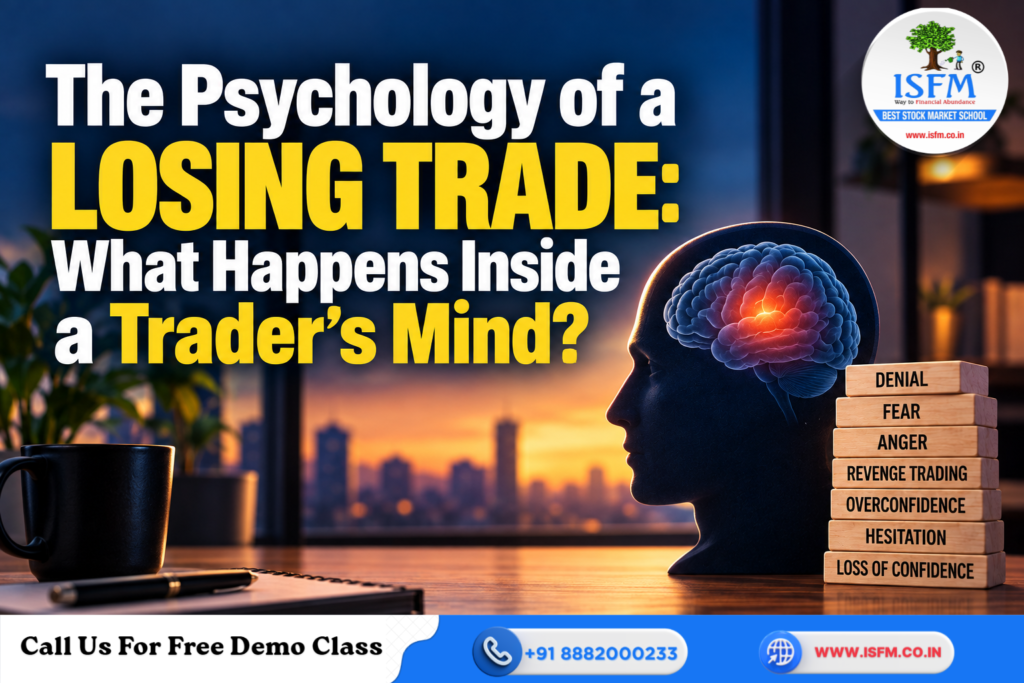
A trader enters a position after analysing the chart, defining a target, and placing a stop-loss. The market moves against the trade, the stop gets hit, and the position closes at a loss. Technically, the trade is over. Psychologically, however, it may not be. For Sushil Alewa, SEBI Registered Research Analyst (INH100009433), MBA and CFP, who has extensive experience in trading, financial education and market analysis, trading psychology is an important part of understanding why traders behave differently after similar market outcomes. The market event may be over, but the emotional reaction can continue. This is why understanding the psychology of a losing trade matters. Behavioural finance studies how emotions, mental shortcuts and cognitive biases influence financial decisions. Prospect theory suggests that people evaluate outcomes relative to a reference point, such as their entry price, and may become more willing to take risks when facing losses. The First Reaction: Disbelief and Denial After a losing trade, the first response may be disbelief. A trader might think: This can lead to confirmation bias—looking for information that supports the original view while ignoring evidence that contradicts it. But a losing trade does not automatically mean the analysis was poor. A valid setup can fail because markets operate through probabilities, not certainty. For traders who want to understand how charts, market structure, indicators and risk management can support a more systematic decision-making process, ISFM’s Technical Analysis Course covers areas including chart reading, price action, stop-loss management and trading psychology. The important question is not “Was I right?” but “Did I follow my process?” Loss Aversion and the Pain of Losing Loss aversion describes the tendency for losses to carry greater psychological weight than comparable gains. For traders, this can appear as: The danger is that the trader stops thinking about the probability of the next trade and starts thinking about the money lost on the previous trade. This becomes particularly important in leveraged markets. Traders dealing with Nifty, Bank Nifty and other derivatives need to understand both the mechanics of the instrument and the emotional consequences of risk. ISFM’s Options Trading Strategy Course covers options, Greeks, volatility, risk management and trading psychology. Anger, Ego, and the Need to Be Right A losing trade can also challenge a trader’s ego. Instead of treating the loss as one outcome in a probabilistic process, the trader may interpret it personally: This attachment to being right can become dangerous. The trader may remain attached to a prediction instead of responding to changing market information. The market does not know the trader’s entry price, opinion or confidence level. It simply continues to move. Revenge Trading: When Recovery Becomes the Goal Revenge trading occurs when a trader enters another position primarily to recover a previous loss rather than because a valid setup exists. Consider a simple example. A trader loses ₹2,000 on a planned trade. Frustrated, they immediately enter another position and decide to risk ₹5,000, thinking, “I will recover the ₹2,000 quickly.” If that trade fails, the original ₹2,000 loss has now become part of a much larger problem. The cycle often looks like this: Loss → emotional discomfort → anger/denial → urge to recover → impulsive trade → larger loss Revenge trading is therefore not a strategy. It is an emotional attempt to remove the discomfort created by the previous result. The Opposite Reaction: Fear After a Loss Not every trader becomes aggressive after losing. Some become afraid. They may skip the next valid setup, exit profitable trades too early, reduce position size irrationally, or completely change their strategy after a small series of losses. This creates another problem: inconsistent execution. A tested trading plan cannot produce meaningful results if it is followed only when the trader feels confident. The goal is not to eliminate fear. It is to prevent fear from making the trading decisions. Overconfidence Can Create Another Psychological Trap Interestingly, the psychological problem can also begin after a winning trade. A trader who experiences several successful trades may increase position size too quickly, take lower-quality setups, or assume that recent success proves superior skill. Research on behavioural biases has associated overconfidence with increased trading activity and risk-taking. This is one reason systematic approaches can be useful. Traders interested in reducing the role of impulsive decisions through rules, automation and systematic execution can explore ISFM’s Algo Trading Course. So both sides can be dangerous: How to Handle a Losing Trade? A healthier response begins with separating the result from the quality of the decision. After a loss: A trading journal can be particularly useful because it replaces emotional memory with actual records. For traders who want to develop broader understanding beyond charts and short-term price movements, ISFM’s Fundamental Analysis Course focuses on financial statements, valuation, company analysis and investment decision-making. Build Systems That Protect Your Mind Discipline should not depend entirely on willpower. Practical safeguards can include: Small, controlled losses are generally easier to process than oversized losses that threaten the trader’s overall capital. For traders interested in more structured approaches to market risk and price relationships, ISFM’s Arbitrage Trading Course introduces concepts around arbitrage, derivatives, risk management and systematic trading frameworks. The Right Meaning of a Loss A losing trade can provide useful information. Ask: Was the setup valid? Was the market condition appropriate? Was the position too large? Was the entry late? Was the stop logical? Did emotion influence the decision? The objective of trading psychology is not to make losses disappear. Losses are unavoidable in a probabilistic market approach. The objective is to prevent one loss from controlling the next decision. Conclusion A trader’s real psychological challenge is often revealed after a losing trade, not after a winning one. The market event may last only a few minutes, but the emotional reaction can influence hours, days or even weeks of decisions. A losing trade is only one outcome. The trader’s reaction to it determines whether it remains a small business expense or becomes the beginning of a much larger problem. Financial

NISM Series V-A Mutual Fund Distributor Exam
Blog

NISM Series V-A Mutual Fund Distributor: How to Pass in 15 Days

If you are planning to enter the mutual fund distribution industry, the NISM Series V-A: Mutual Fund Distributors Certification Examination is one of the most important certifications to understand. The good news is that you do not necessarily need months of preparation. With a focused strategy, the right study material and consistent revision, 15 days can be enough for a well-planned preparation schedule. What Is NISM Series V-A? NISM Series V-A: Mutual Fund Distributors Certification Examination is a certification examination conducted by the National Institute of Securities Markets (NISM). The examination focuses on concepts that a mutual fund distributor should understand before dealing with investors and mutual fund products. Its objectives include understanding mutual fund concepts, different schemes, distribution, scheme evaluation, regulations, taxation, valuation and financial planning. The certification is particularly relevant for: NISM states that the certification serves as a common minimum knowledge benchmark for persons involved in mutual fund sales and distribution. NISM Series V-A Exam Pattern 2026 Before preparing, understand the examination structure. Particular Details Examination NISM-Series-V-A: Mutual Fund Distributors Questions 100 Maximum Marks 100 Duration 2 Hours Question Type Multiple Choice Questions Passing Score 50% Negative Marking No Examination Fee ₹1,500 Certificate Validity 3 Years According to NISM’s current certification information, the examination contains 100 questions carrying 100 marks, has a 2-hour duration, requires 50% to pass, and has no negative marking. The current fee is ₹1,500, and the certificate validity is 3 years. An Important Advantage: No Negative Marking One of the biggest advantages of the NISM V-A examination is that there is no negative marking. Therefore, candidates should avoid leaving questions unanswered. If you are unsure about an answer, use the elimination method and attempt the question. How to Use the NISM Workbook Effectively? One of the biggest mistakes candidates make is collecting multiple books, PDFs, videos and question banks without completing the official material. NISM provides study material/workbook for candidates after enrolment. Use it in three stages: Identify: Third Reading — Revise Do not read everything again. Concentrate on highlighted portions and your mistake notebook. NISM V-A Mock Tests: Why They Matter Mock tests are one of the most effective ways to prepare. The examination has 100 questions in 120 minutes, which means you have approximately 72 seconds per question on average. Therefore, practice is important not only for knowledge but also for speed. Recommended Target Before appearing for the examination, try to consistently score: 70–80+ marks in quality mock tests. Why target 70–80 when the official passing score is 50? Because entering the examination with a large safety margin is much better than preparing only to score 50. Can a Beginner Pass NISM V-A in 15 Days? Yes, it is possible—but it is not guaranteed. A beginner can prepare within 15 days if they: If you have no finance background, you may need more time for certain concepts. But a disciplined 15-day plan can provide a realistic preparation framework. NISM V-A vs Other NISM Certifications NISM offers several certifications for different functions in India’s securities markets. The Series V-A certification is specifically focused on mutual fund distribution. It should not be confused with the newer Series V-D, which covers Mutual Fund and Specialized Investment Fund distribution and became available from July 22, 2026. Therefore, candidates should carefully identify the certification required for their particular role before registering. What Can You Do After Passing NISM V-A? Passing the examination can be an important step toward a career in mutual fund distribution. Potential career paths include: However, passing NISM V-A alone does not automatically make someone a SEBI-registered investment adviser. Distribution and investment advisory are different functions with different regulatory requirements. This distinction is extremely important for anyone planning a career in financial services. Conclusion The NISM Series V-A Mutual Fund Distributor examination is not an impossible exam. With 15 days of disciplined preparation, a beginner can build sufficient conceptual understanding and exam confidence. The winning formula is simple: Official Workbook + Conceptual Understanding + Daily Revision + Mock Tests + Mistake Analysis = Better Chance of Passing Remember that the official passing requirement is 50%, with 100 questions, 100 marks, 2 hours and no negative marking. Instead of preparing just to cross the passing line, aim for 70–80% in your practice tests. That safety margin can make a significant difference on the actual examination day. If your goal is to build a career in mutual fund distribution, wealth management or financial services, NISM Series V-A can be a useful starting point for developing industry-specific knowledge.

Fundamental Analysis vs Technical Analysis
Blog

Fundamental Analysis vs Technical Analysis: Which Should Investors Learn First?

When beginners enter the stock market, one question often appears early: Should I learn fundamental analysis or technical analysis first? Think of the two methods as two different ways of looking at the same market. Fundamental analysis studies the health, earning power, and future potential of a business. Technical analysis studies price movement, volume, trends, and market behaviour. It is similar to choosing between studying a company’s health report and studying its price chart. Neither method is automatically better. The right starting point depends on whether you want to become a long-term investor, swing trader, or intraday trader. According to Sushil Alewa, SEBI Registered Research Analyst (INH100009433), the right analysis method should match an investor’s objective, time horizon and risk-taking ability. This distinction is particularly important for beginners entering India’s NSE and BSE markets. What Is Fundamental Analysis? Fundamental analysis evaluates a company’s financial health, business quality, growth prospects, competitive position and valuation. An investor may study revenue and profit growth, earnings per share, cash flow, debt, interest coverage, profit margins, return on equity, return on capital, management quality and industry conditions. Valuation ratios such as P/E, P/B, PEG and EV/EBITDA can also help investors assess whether the market price appears reasonable compared with the company’s earning potential. For example, someone planning to hold an NSE-listed company for five years may examine its annual reports, balance sheet, cash flows, debt levels and future growth opportunities before investing. Beginners who want to build these skills systematically can explore an Fundamental Analysis Course to understand financial statements, valuation techniques and business analysis in a structured manner. Fundamental analysis is therefore commonly associated with long-term investing, although it can also support other investment decisions. What Is Technical Analysis? Technical analysis focuses primarily on market-generated information, especially price and volume. Instead of asking, “What is this company worth?” a technical analyst may ask, “What is the price doing right now?” Common tools include trends, support and resistance, candlestick patterns, moving averages, momentum indicators, breakouts, volume, volatility and chart patterns. For instance, a trader analysing Nifty or Bank Nifty may use a moving average, support levels and volume to identify a potential trading setup. A swing trader may hold a position for several days or weeks, while an intraday trader may focus on movements lasting only minutes or hours. Anyone interested in developing these skills can study a structured Technical Analysis Course covering charts, indicators, price action, trends and trading setups. Technical analysis can therefore be particularly useful for entry, exit and risk-management decisions. Fundamental Analysis vs Technical Analysis Factor Fundamental Analysis Technical Analysis Main focus Business and financial health Price, volume and market behaviour Main question What may be worth owning? When might price move? Typical horizon Months to years Minutes to months Key tools Financial statements and valuation ratios Charts, trends, indicators and volume Common users Investors and portfolio builders Traders and tactical participants Main risk Incorrect growth or valuation assumptions False signals and overtrading These are broad tendencies, not strict rules. Investors can use charts, and traders can consider fundamentals. Who Should Learn Fundamental Analysis First? Fundamental analysis for beginners is generally a sensible starting point for people who want to build a long-term portfolio. It may suit someone who wants to understand businesses, invest with lower trading frequency, has limited time to monitor charts, or wants to evaluate whether a declining share price reflects temporary market weakness or deteriorating business fundamentals. A beginner should learn how to read an income statement, balance sheet and cash-flow statement, along with basic valuation metrics and business risks. Who Should Learn Technical Analysis First? Technical analysis for beginners may be a more relevant starting point for someone whose primary objective is swing trading or intraday trading. If your focus is Nifty, Bank Nifty or individual NSE stocks, technical analysis can help you understand market structure, identify potential setups, plan entries and exits, and define stop-loss levels. However, learning charts does not make trading easy. Active traders need position sizing, risk limits, discipline and a well-tested trading plan. For traders who later want to move beyond manual strategies, an Algo Trading Course can introduce systematic trading concepts and the use of technology to execute rule-based strategies. Why Risk Management Comes Before Both A person can understand financial statements and charts yet still lose money through poor position sizing or emotional decisions. Before using real money, beginners should understand: This becomes particularly important when moving into derivatives. Anyone considering options should first understand how leverage, volatility, option Greeks and time decay affect positions. A structured Options Trading Course can help learners build that foundation before experimenting with complex strategies. Can You Combine Both Methods? Absolutely. In fact, many market participants use both. Consider a simple example. An investor identifies an NSE-listed company with strong revenue growth, manageable debt, healthy cash flows and attractive long-term prospects through fundamental analysis. Instead of immediately buying, the investor studies the chart. The stock is approaching an established support zone while volume and price structure show improving momentum. Here, fundamentals help answer “What could be worth owning?”, while technical analysis helps answer “When might the entry be more appropriate?” The same framework can be adapted for swing trading, although the time horizon and risk controls will be different. Common Beginner Mistakes Beginners often make mistakes such as using too many indicators, buying low-P/E stocks without checking earnings quality, assuming every chart pattern will work, following tips instead of developing a process, overtrading, using excessive leverage, and confusing a profitable trade with a good investment. Another common mistake is switching constantly between investing and trading without clearly defining the objective. A Simple Learning Roadmap Start by learning stock-market basics and financial risk. Then decide whether your primary goal is investing or trading. Long-term investors can begin with fundamentals and gradually learn technical analysis for timing. Active traders can start with technical analysis but should simultaneously develop risk-management skills. For beginners looking for a broader foundation covering multiple areas of the market, a

How Time Decay Quietly Eats an Option Buyer’s Capital
Blog

How Time Decay Quietly Eats an Option Buyer’s Capital?

Imagine a trader buys a Nifty Call expecting the index to rise. The trader is confident about the direction, but Nifty remains almost unchanged for the next two days. There is no major crash, no wrong prediction and no dramatic reversal. Yet the option premium has fallen significantly. So, if the market barely moved, where did the option’s value go? The answer is time decay, commonly measured by a Greek called theta. According to Sushil Alewa, SEBI Registered Research Analyst (INH100009433), an option buyer is not only taking a view on direction but also paying for time. Every passing day reduces the amount of time available for the expected move to happen. What Is Time Decay in Options? Time decay refers to the gradual reduction in an option’s value as it gets closer to expiry. Theta represents the theoretical change in an option’s value caused by one day passing, assuming other important variables remain unchanged. For a long option position, Calls and Puts generally have negative theta. Option sellers generally benefit from the passage of time, all else being equal. Theta is commonly expressed as an estimated daily change in premium. For example, suppose an option is trading at ₹100 and has a theta of -₹5. If everything else remains unchanged, its theoretical value could fall to approximately ₹95 after one day. Actual prices, however, can move differently because option premiums are also affected by the underlying price, implied volatility, interest rates, liquidity and other factors. For traders wanting to understand how theta interacts with other option Greeks, volatility and option pricing, structured learning through an Options Trading Strategy Course can help build that foundation. Intrinsic Value vs Time Value An option premium can broadly be understood as: Option Premium = Intrinsic Value + Time Value Intrinsic value is the value an option already has because it is in the money. Time value is the additional amount traders pay for the possibility of a favourable future move. As expiry approaches, there is less time available for that move to happen. Therefore, time value gradually decreases. At expiry, an option’s value is primarily determined by its intrinsic value. An out-of-the-money option may expire worthless. This is why options are often described as wasting assets. The clock is constantly working against the buyer. Understanding intrinsic value, time value, volatility and expiry together is an important part of learning derivatives. Traders looking for a broader understanding can explore ISFM’s Advanced Derivatives learning program. Why Theta Accelerates Near Expiry? Time decay is not linear. When an option has several weeks or months remaining, the daily erosion may appear relatively manageable. But as expiry approaches, the rate of decay can become much faster, particularly for at-the-money and short-dated options. Think of an ice cube. It may appear to melt slowly at first, but as the remaining piece becomes smaller, it can disappear surprisingly quickly. This is particularly relevant for weekly options, expiry-day contracts and zero-days-to-expiry options. The reason is simple: the market has less and less time to deliver the expected move. Why At-the-Money Options Are Particularly Vulnerable At-the-money options often contain substantial time value while having little or no intrinsic value. Suppose Nifty is trading near a Call’s strike price. If Nifty remains around that level while expiry approaches, the option can lose value rapidly because there is less time for a meaningful profitable move. Deep in-the-money options contain more intrinsic value, while out-of-the-money options may have relatively low premiums but can still decay toward zero. Therefore, a cheap option does not automatically mean a low-risk option. How Time Decay Eats an Option Buyer’s Capital? Consider a hypothetical Bank Nifty Call purchased at ₹120. The trader expects a strong upward move. Instead, Bank Nifty remains range-bound for two days. At the same time, implied volatility falls slightly. The option premium drops from ₹120 to ₹75. The ₹45 decline may be the result of several factors working together: The trader may say, “I was not wrong about the direction.” But being directionally correct is not always enough. An option buyer needs the underlying asset to move in the expected direction, by a sufficient distance and within a suitable time period. Direction Alone Is Not Enough Imagine buying a Nifty Call because you expect Nifty to rise. Nifty eventually rises, but the move happens only after the option has lost most of its time value or after expiry. The trader may have been correct about the broader direction but still lost money on the option. This is one of the most important lessons in options trading for beginners: You are not only predicting direction. You are also predicting timing. The expected move must happen quickly enough to overcome the premium paid and the erosion caused by time. Technical analysis can help traders evaluate whether price has the potential to make the required move. Studying trends, price action, support, resistance and market structure through a Technical Analysis Course can complement an understanding of option pricing. The Role of Implied Volatility Theta is only one piece of the option-pricing puzzle. Implied volatility (IV) also has a major influence on option premiums. Rising IV can support an option’s premium, while falling IV can reduce it. This becomes particularly important around major events. An option may be purchased when volatility is elevated, but after the event passes, IV can decline sharply — a phenomenon often called volatility crush. Therefore, an option buyer can effectively be fighting two forces: The clock and the volatility price. Even if the underlying moves slightly in the correct direction, falling IV and time decay can reduce the premium. How Traders Can Manage Time Decay? Traders cannot eliminate theta from long options, but they can manage their exposure to it. Some practical considerations include: Time decay should also be considered alongside position sizing, capital allocation and risk management. These broader trading foundations are important for anyone building a disciplined approach to the market and are covered within ISFM’s Chartered Stock Trading Expert (CSTX) program. No

Scroll to Top
Get Free Demo Class in Live Market Trading
Be an Expert
Stock Trader

Just in One Month

16+

Years of Experience

30,000

Students Trained


Call Now