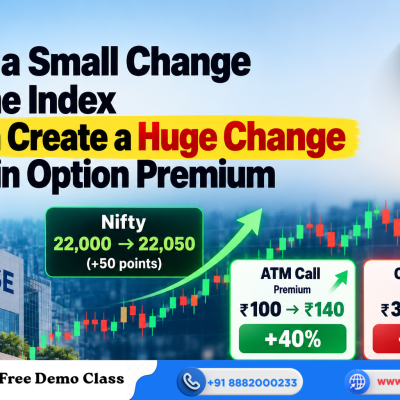
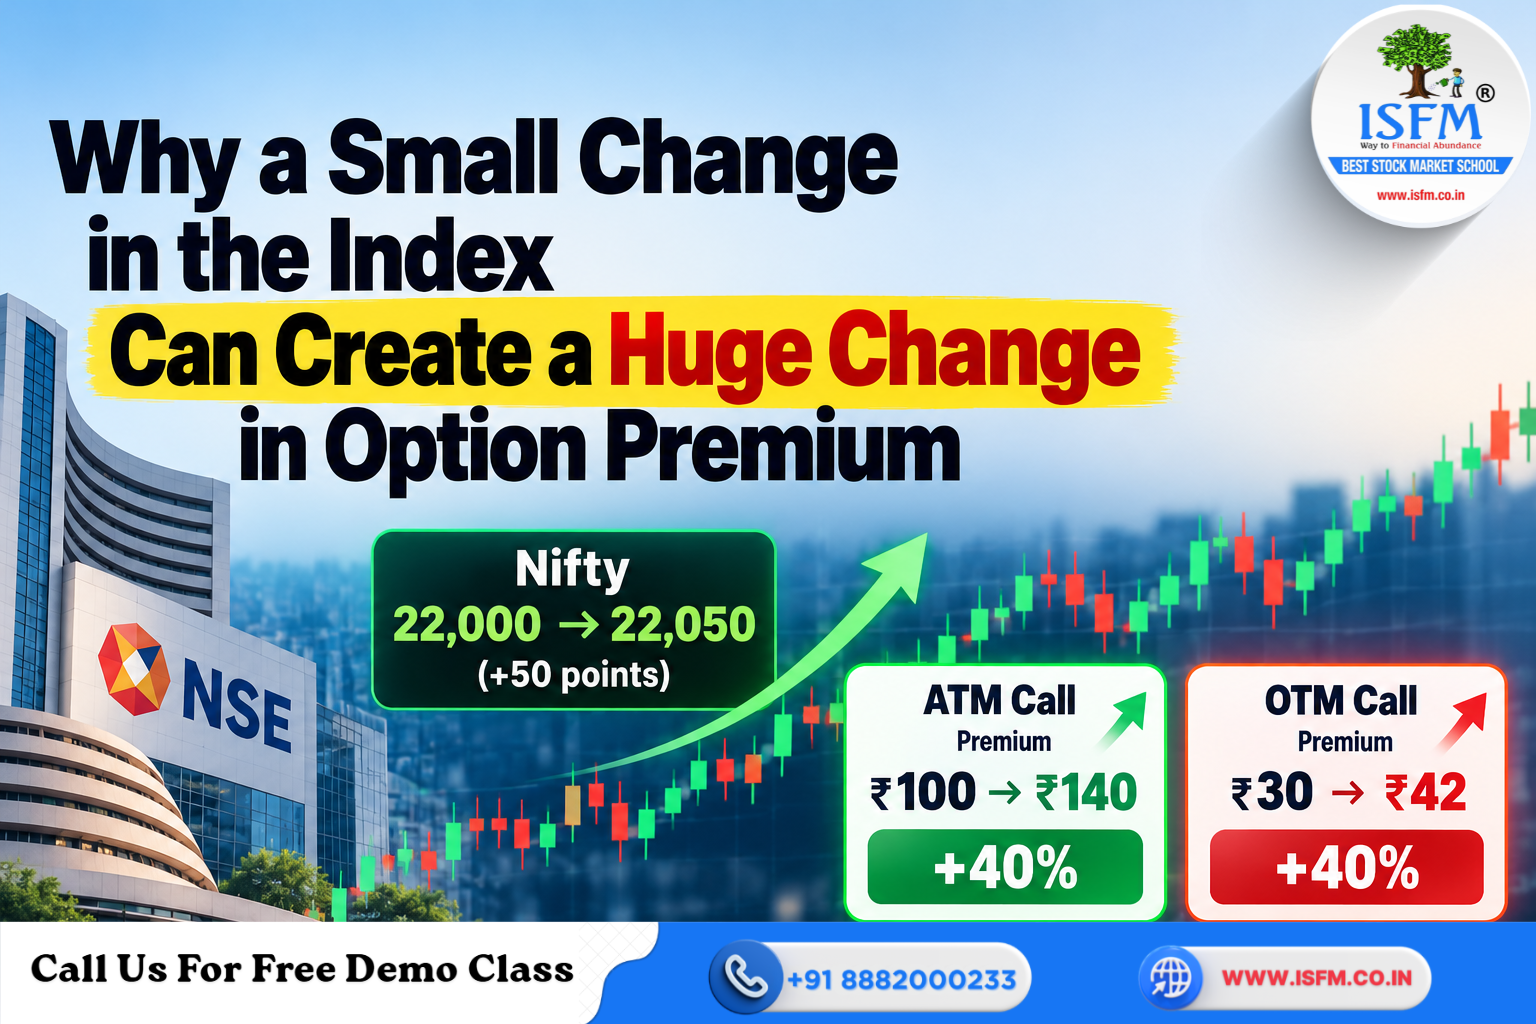
Imagine Nifty is trading at 22,000 and rises by 50 points to 22,050, a move of approximately 0.23%. During this movement, two hypothetical Call options show the following changes:
- ATM Call: Premium rises from ₹100 to ₹140, a gain of ₹40 or 40%.
- OTM Call: Premium rises from ₹30 to ₹42, a gain of ₹12 or 40%.
Both options deliver the same percentage gain, but their absolute gains differ. These figures are illustrative, not a prediction. Actual premium changes depend on the option’s Greeks, time to expiry, implied volatility and liquidity.
Why can a small index move create such a large percentage change in an option premium?
According to Sushil Alewa, SEBI Registered Research Analyst (INH100009433), understanding option pricing is essential for managing risk in derivatives trading. Traders should examine delta, gamma, time decay and implied volatility rather than focusing only on the direction of Nifty, Bank Nifty or an individual stock. Beginners can strengthen their foundation through a stock market investment course.
Options Are Leveraged Instruments
Options allow traders to gain exposure to Nifty, Bank Nifty or an individual stock by paying a relatively small premium compared with the underlying exposure.
This creates leverage. A small percentage change in the underlying can produce a much larger percentage change in the option premium. For example, a ₹100 option gaining ₹30 delivers a 30% premium gain, even if the index moves only a fraction of a percent.
However, leverage works in both directions. An unfavourable price move, time decay or falling implied volatility can quickly reduce the premium. An option buyer can lose the entire premium paid if the contract expires worthless.
Delta: The First Driver of Premium Movement
Delta estimates how much an option premium may change for a one-point move in the underlying.
Estimated premium change = Delta × Change in underlying
Consider a 50-point rise in Nifty:
- A Call with a delta of 0.50 may gain approximately 25 premium points.
- A Call with a delta of 0.80 may gain approximately 40 premium points.
- A Put with a delta of -0.50 may lose approximately 25 premium points.
These are estimates, not guarantees. Delta changes as the underlying moves, and the final premium also depends on volatility, time decay and liquidity.
Gamma: Why Delta Does Not Stay Constant
Delta tells traders how sensitive an option is to the underlying. Gamma explains how quickly that sensitivity changes.
Suppose a Call has a delta of 0.40 and gamma of 0.05. For a one-point rise in the underlying, its delta may increase to approximately 0.45, assuming other factors remain constant.
As the underlying continues moving favourably, delta may rise further, making the Call increasingly responsive to additional price changes.
This is why option premiums can accelerate during a strong move. Gamma is generally highest near the at-the-money (ATM) strike and becomes particularly important as expiry approaches. A small index move can therefore change an option’s behaviour rapidly.
Understanding price movements and market behaviour is also important for derivatives traders. A structured technical analysis course can help learners develop their chart-reading and analytical skills.
Why ATM Options React Most Sharply
ATM options sit close to the underlying’s current price. Their delta is often around 0.50, and their gamma is typically high relative to comparable options farther from the money.
Much of an ATM option’s premium consists of time value rather than intrinsic value. A modest move can quickly change the probability of the option finishing in the money.
For example, an ATM Call priced at ₹100 might rise to ₹130 after a favourable 50-point Nifty move. That is a 30% premium gain from a comparatively small index movement. The reverse is equally important: an unfavourable move can rapidly reduce its premium.
Why OTM Options Can Move Violently
Out-of-the-money (OTM) options have no intrinsic value and consist entirely of time value. Because their premiums are relatively cheap, even a small absolute change can represent a large percentage gain or loss.
An OTM Call may initially respond weakly because its delta is low. If Nifty approaches its strike, however, delta and gamma can increase, causing the premium to rise sharply.
But cheap does not mean safe. If the expected move fails to occur before expiry, the option can lose most or all of its premium. Traders should understand strike selection, pricing and derivatives risk before trading weekly contracts. Exploring relevant stock market courses can help build this knowledge systematically.
The Role of Implied Volatility
Implied volatility (IV) reflects the market’s expectations of future price fluctuations as implied by option prices. Higher IV generally increases premiums, while lower IV generally reduces them, all else being equal.
Before major events, traders may bid up option premiums in anticipation of larger movements. After the event, IV can fall sharply, producing a volatility crush.
Consequently, a trader can correctly predict Nifty’s direction and still lose money if the underlying move is insufficient to offset falling IV and time decay.
Why Weekly Options Become Riskier Near Expiry
Weekly options have limited time for the expected move to occur. As expiry approaches, time decay can become particularly severe for options with substantial time value.
At the same time, ATM options can exhibit very high gamma. A small movement in Nifty or Bank Nifty may cause rapid premium changes, while a reversal can erase gains just as quickly.
This combination of gamma and theta makes near-expiry trading especially demanding. Traders may need a sufficiently fast move to overcome the premium lost through time decay.
A Practical Nifty Example
Suppose Nifty trades at 22,000 and a trader buys the 22,000 Call for ₹100. Assume its delta is 0.50 and gamma is 0.02 per index point.
Nifty rises to 22,050, a gain of 50 points, or approximately 0.23%. Using a simplified constant-gamma estimate:
- Initial delta: 0.50
- Estimated premium change from delta: 0.50 × 50 = 25 points
- Estimated additional change from gamma: ½ × 0.02 × 50² = 25 points
The estimated premium becomes ₹150, representing a 50% increase before accounting for changes in implied volatility, time decay and other factors. Actual premiums may differ substantially because delta and gamma change throughout the move, and other pricing factors may also change.
This example illustrates how gamma can magnify the effect of an underlying move. It is not a market prediction.
Why Option Sellers Face Different Risks
Option sellers receive premiums but accept contractual obligations. A small adverse move can create substantial losses, particularly in naked short positions.
Gamma can rapidly increase their directional exposure, while overnight gaps may cause losses much larger than the premium received. Margin requirements may also rise during volatile markets.
Defined-risk spreads can cap maximum losses, but they also limit potential profits. Option selling is not automatically safer than buying.
How Traders Can Manage This Risk
Before entering a trade, traders should:
- Check delta, gamma and the option’s moneyness.
- Understand the time remaining until expiry.
- Monitor implied volatility and bid-ask spreads.
- Avoid illiquid strikes and oversized positions.
- Define the maximum acceptable loss beforehand.
- Consider defined-risk strategies where appropriate.
- Avoid averaging down without a tested plan.
- Reduce position size when near-expiry risks increase.
Developing a disciplined trading process requires consistent attention to position sizing, risk assessment and decision-making. Traders seeking structured learning can explore the Chartered Stock Trading Expert course.
Frequently Asked Questions
Why does an option premium rise faster than the index?
Leverage, delta and gamma can make an option premium increase disproportionately compared with the underlying index.
Why do ATM options have high gamma?
ATM options are particularly sensitive to changes in the underlying price, especially near expiry, so their delta can change rapidly.
Can an option premium fall even when Nifty moves in my favour?
Yes. Falling implied volatility and time decay can offset gains from a favourable index movement.
Are weekly options riskier than monthly options?
Weekly options can experience sharper time decay and rapid gamma-driven price changes near expiry, making risk management especially important.
Conclusion
A small index move can create a large option-premium move because options combine leverage, changing delta, gamma, time decay and volatility. Successful trading requires understanding these forces rather than focusing only on whether the market will rise or fall.
Readers who want to continue learning about financial markets, trading strategies and risk management can explore ISFM’s stock market training resources.
In options trading, the index may move a little, but the premium can move a lot. That is the power—and the danger—of option leverage.
Financial risk disclaimer: This article is for educational purposes only and is not investment advice. Options trading involves substantial risk and may result in significant financial losses. Evaluate your financial situation and risk tolerance before trading.