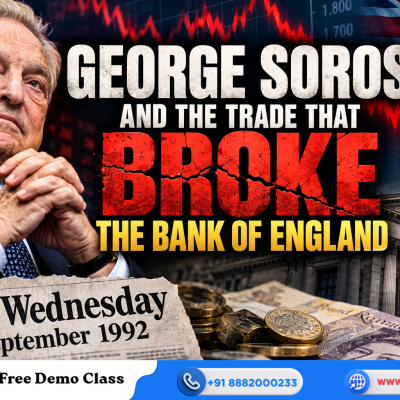
In September 1992, Soros’s Quantum Fund bet heavily against the British pound. When Britain abandoned its exchange-rate commitment, the fund reportedly earned approximately $1 billion. The episode became known as Black Wednesday, earning Soros the nickname “the man who broke the Bank of England.” However, he was one of several investors betting against sterling, not the sole cause of the crisis.
According to Sushil Alewa, SEBI Registered Research Analyst (INH100009433), understanding macroeconomic forces and market psychology is essential for recognising how major financial events unfold. George Soros’s famous 1992 sterling trade demonstrates how economic fundamentals, government policy, and market expectations can collide.
Who Was George Soros?
George Soros is a Hungarian-born investor, philanthropist, and founder of the Quantum Fund. He became renowned for global macro investing, an approach that seeks opportunities based on economic trends, interest rates, currencies, and government policies.
Soros also developed the concept of reflexivity, which explores how investors’ perceptions can influence market prices and, in turn, the economic conditions they are evaluating.
His 1992 currency trade became one of the most famous examples of macroeconomic analysis influencing financial markets.
What Was the European Exchange Rate Mechanism?
The European Exchange Rate Mechanism (ERM) was designed to reduce exchange-rate fluctuations between participating European currencies and support closer monetary cooperation.
Britain joined the ERM in October 1990. Under the arrangement, the pound had to remain within an agreed exchange-rate band against other participating currencies, including Germany’s Deutsche mark.
The problem was that maintaining this commitment became increasingly difficult as Britain’s economic conditions diverged from Germany’s. The ERM crisis exposed the challenges of defending an exchange-rate target when domestic economic priorities demanded a different policy.
Understanding how economic conditions affect financial markets is a key part of ISFM’s Fundamental Analysis Course.
Why Was the British Pound Vulnerable?
Three major factors created pressure on sterling.
1. Britain was in recession. The UK economy was struggling, and lower interest rates could have supported borrowing, spending, and economic recovery.
2. German interest rates remained high. Following German reunification, the Bundesbank maintained relatively tight monetary conditions to address inflationary pressures. These policies made German assets attractive and complicated Britain’s efforts to maintain the pound’s exchange rate.
3. The pound appeared overvalued. Many currency traders believed sterling was trading at an unsustainable level relative to Germany’s Deutsche mark and Britain’s economic fundamentals.
Britain faced a policy conflict: cutting interest rates could weaken the pound, while raising them to defend sterling could deepen the domestic recession.
Soros and other investors recognised that maintaining the ERM commitment could become increasingly expensive and politically difficult. Understanding how economic announcements and market expectations influence price movements is also relevant to learners pursuing ISFM’s Technical Analysis Course.
How Soros Shorted the Pound?
Short selling a currency means selling it with the expectation of buying it back later at a lower price.
For example, if a trader sells pounds when one pound is worth $2 and later repurchases them at $1.80, the trader makes a profit before financing costs and other expenses. If the pound rises instead, the position loses money.
Soros’s Quantum Fund established a substantial short position against sterling. Reports commonly describe the fund’s exposure as running into billions of dollars, although exact figures vary across accounts.
The strategy was based on a macroeconomic thesis rather than a simple prediction that the pound would fall. Soros believed the UK government would eventually struggle to maintain its exchange-rate commitment.
Directional market strategies and the importance of managing potential losses are concepts that learners can explore through ISFM’s Options Trading Course.
Black Wednesday: 16 September 1992
On 16 September, selling pressure against sterling intensified. The British government and the Bank of England attempted to defend the pound through emergency measures.
The government announced an interest-rate increase from 10% to 12%, with a further increase to 15% announced but never implemented. The Bank of England also intervened in currency markets, using foreign-exchange reserves to purchase pounds.
These actions failed to restore confidence. Traders continued selling sterling, and defending the exchange-rate band became increasingly difficult.
That evening, Britain announced its withdrawal from the ERM. Sterling was subsequently allowed to float more freely and depreciated.
The event became known as Black Wednesday. The Bank of England had not literally been broken; rather, the government’s exchange-rate policy had become unsustainable under prevailing economic and market conditions.
Why Soros’s Trade Worked
Several factors contributed to the trade’s success:
- Macroeconomic insight: Soros identified the conflict between Britain’s domestic economic needs and its exchange-rate commitment.
- Policy awareness: He understood that the government had limited options if market pressure continued.
- Market positioning: The fund established a large short position before the decisive policy change.
- Conviction and risk-taking: The strategy required accepting substantial potential losses if sterling remained supported.
The outcome was not guaranteed. Had Britain successfully defended the pound or changed its economic policies differently, the trade could have produced significant losses.
Understanding exposure, leverage, and risk is equally important when studying ISFM’s Advanced Derivatives Course.
The Billion-Dollar Profit and Its Aftermath
Soros’s Quantum Fund reportedly made around $1 billion from the sterling trade, although estimates vary depending on the positions and accounting periods considered.
For Britain, leaving the ERM damaged the government’s economic credibility and became a major political setback. Sterling depreciated, but the subsequent reduction in interest-rate constraints gave policymakers greater flexibility to support the domestic economy.
Black Wednesday remains a defining moment in British financial history and an important episode in the evolution of European monetary integration.
Lessons for Traders and Investors
Soros’s success offers several lessons for anyone studying financial markets:
- Understand the fundamentals: Currency prices reflect interest rates, inflation, economic growth, and policy decisions.
- Recognise policy conflicts: Government commitments can become vulnerable when they contradict economic realities.
- Respect risk: Large positions can generate enormous profits but also expose traders to substantial losses.
- Consider timing: A correct market view can still lose money if the anticipated move takes too long.
- Avoid blind imitation: A historic trade cannot be copied successfully without understanding its economic context, financing, and downside exposure.
For learners interested in systematic, rule-based trading approaches, ISFM’s Algo Trading Course introduces concepts behind algorithmic trading and strategy development.
These lessons demonstrate why disciplined analysis, risk management, and an understanding of market behaviour matter more than simply following a famous trader’s moves.
Conclusion
George Soros’s 1992 sterling trade became legendary because it combined macroeconomic insight, a bold position, and a historic policy failure. Yet the episode was not the achievement of one trader alone: broader market pressure exposed the limitations of Britain’s exchange-rate commitment.
The trade that broke the Bank of England was not just a bet against a currency. It was a bet that economic reality would eventually overpower political commitment.
Financial risk disclaimer: This article is for educational and informational purposes only. Currency trading, leveraged positions, and derivatives involve substantial risks, including the potential loss of invested capital. Historical performance does not guarantee future results.