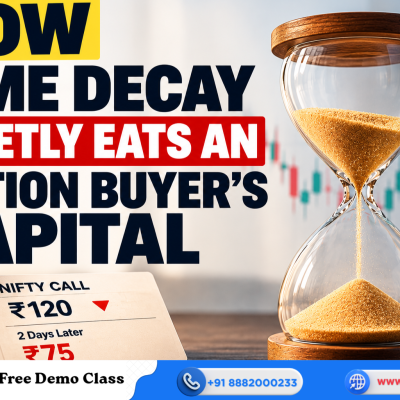
Imagine a trader buys a Nifty Call expecting the index to rise. The trader is confident about the direction, but Nifty remains almost unchanged for the next two days. There is no major crash, no wrong prediction and no dramatic reversal. Yet the option premium has fallen significantly.
So, if the market barely moved, where did the option’s value go?
The answer is time decay, commonly measured by a Greek called theta.
According to Sushil Alewa, SEBI Registered Research Analyst (INH100009433), an option buyer is not only taking a view on direction but also paying for time. Every passing day reduces the amount of time available for the expected move to happen.
What Is Time Decay in Options?
Time decay refers to the gradual reduction in an option’s value as it gets closer to expiry. Theta represents the theoretical change in an option’s value caused by one day passing, assuming other important variables remain unchanged.
For a long option position, Calls and Puts generally have negative theta. Option sellers generally benefit from the passage of time, all else being equal. Theta is commonly expressed as an estimated daily change in premium.
For example, suppose an option is trading at ₹100 and has a theta of -₹5. If everything else remains unchanged, its theoretical value could fall to approximately ₹95 after one day.
Actual prices, however, can move differently because option premiums are also affected by the underlying price, implied volatility, interest rates, liquidity and other factors.
For traders wanting to understand how theta interacts with other option Greeks, volatility and option pricing, structured learning through an Options Trading Strategy Course can help build that foundation.
Intrinsic Value vs Time Value
An option premium can broadly be understood as:
Option Premium = Intrinsic Value + Time Value
Intrinsic value is the value an option already has because it is in the money.
Time value is the additional amount traders pay for the possibility of a favourable future move.
As expiry approaches, there is less time available for that move to happen. Therefore, time value gradually decreases.
At expiry, an option’s value is primarily determined by its intrinsic value. An out-of-the-money option may expire worthless.
This is why options are often described as wasting assets. The clock is constantly working against the buyer.
Understanding intrinsic value, time value, volatility and expiry together is an important part of learning derivatives. Traders looking for a broader understanding can explore ISFM’s Advanced Derivatives learning program.
Why Theta Accelerates Near Expiry?
Time decay is not linear.
When an option has several weeks or months remaining, the daily erosion may appear relatively manageable. But as expiry approaches, the rate of decay can become much faster, particularly for at-the-money and short-dated options.
Think of an ice cube. It may appear to melt slowly at first, but as the remaining piece becomes smaller, it can disappear surprisingly quickly.
This is particularly relevant for weekly options, expiry-day contracts and zero-days-to-expiry options.
The reason is simple: the market has less and less time to deliver the expected move.
Why At-the-Money Options Are Particularly Vulnerable
At-the-money options often contain substantial time value while having little or no intrinsic value.
Suppose Nifty is trading near a Call’s strike price. If Nifty remains around that level while expiry approaches, the option can lose value rapidly because there is less time for a meaningful profitable move.
Deep in-the-money options contain more intrinsic value, while out-of-the-money options may have relatively low premiums but can still decay toward zero.
Therefore, a cheap option does not automatically mean a low-risk option.
How Time Decay Eats an Option Buyer’s Capital?
Consider a hypothetical Bank Nifty Call purchased at ₹120.
The trader expects a strong upward move. Instead, Bank Nifty remains range-bound for two days. At the same time, implied volatility falls slightly.
The option premium drops from ₹120 to ₹75.
The ₹45 decline may be the result of several factors working together:
- Time decay
- Lack of sufficient price movement
- Declining implied volatility
- Bid-ask spread
- Transaction costs
The trader may say, “I was not wrong about the direction.”
But being directionally correct is not always enough.
An option buyer needs the underlying asset to move in the expected direction, by a sufficient distance and within a suitable time period.
Direction Alone Is Not Enough
Imagine buying a Nifty Call because you expect Nifty to rise.
Nifty eventually rises, but the move happens only after the option has lost most of its time value or after expiry.
The trader may have been correct about the broader direction but still lost money on the option.
This is one of the most important lessons in options trading for beginners:
You are not only predicting direction. You are also predicting timing.
The expected move must happen quickly enough to overcome the premium paid and the erosion caused by time.
Technical analysis can help traders evaluate whether price has the potential to make the required move. Studying trends, price action, support, resistance and market structure through a Technical Analysis Course can complement an understanding of option pricing.
The Role of Implied Volatility
Theta is only one piece of the option-pricing puzzle.
Implied volatility (IV) also has a major influence on option premiums. Rising IV can support an option’s premium, while falling IV can reduce it.
This becomes particularly important around major events. An option may be purchased when volatility is elevated, but after the event passes, IV can decline sharply — a phenomenon often called volatility crush.
Therefore, an option buyer can effectively be fighting two forces:
The clock and the volatility price. Even if the underlying moves slightly in the correct direction, falling IV and time decay can reduce the premium.
How Traders Can Manage Time Decay?
Traders cannot eliminate theta from long options, but they can manage their exposure to it.
Some practical considerations include:
- Avoid buying very short-dated options without a clear timing advantage.
- Ask whether the expected move can realistically happen before expiry.
- Compare the premium paid with the underlying’s potential movement.
- Avoid holding losing options passively without reassessing the trade.
- Consider longer expiries when the trade thesis requires more time.
- Use defined-risk spreads where appropriate.
- Reduce position size when trading near expiry.
- Monitor theta, delta, gamma and implied volatility together.
- Set an exit plan before entering the trade.
- Never use money required for essential expenses for speculative trading.
Time decay should also be considered alongside position sizing, capital allocation and risk management. These broader trading foundations are important for anyone building a disciplined approach to the market and are covered within ISFM’s Chartered Stock Trading Expert (CSTX) program.
No strategy can guarantee profits, and every approach has its own risks and trade-offs.
Common Mistakes Option Buyers Make
Many option buyer losses come from treating options like ordinary stocks.
Common mistakes include buying cheap out-of-the-money options simply because they look affordable, holding positions until expiry without reassessment, ignoring theta when the underlying remains stagnant, buying near-expiry options without a clear catalyst, averaging down repeatedly and ignoring implied volatility or bid-ask spreads.
Another major mistake is using too much capital on weekly options simply because the premium appears small.
A ₹20 option can still represent 100% of the premium at risk if it expires worthless. For traders interested in moving from discretionary decision-making toward systematic trading, Algo Trading can provide another perspective on rule-based entries, exits and risk-management processes.
Frequently Asked Questions
What is time decay in options?
Time decay is the gradual reduction in an option’s time value as it moves closer to expiry. It is commonly measured using theta and generally works against option buyers.
Why do option buyers lose money when the market does not move?
An option buyer pays for the possibility of a future move. If the underlying remains relatively unchanged, time value can decline as expiry approaches. Falling implied volatility can further reduce the premium.
Do weekly options experience faster theta decay?
Short-dated options can experience rapid time decay, particularly as expiry approaches. The effect can become especially noticeable during the final days and for at-the-money contracts.
Can an option increase in value despite negative theta?
Yes. Theta is only one factor affecting an option’s price. A sufficiently large favourable move in the underlying, or an increase in implied volatility, can increase the option premium despite the negative effect of time decay.
Is buying a cheap out-of-the-money option low risk?
No. A low premium does not necessarily mean low risk. An out-of-the-money option can lose most or all of its premium and may expire worthless.
Conclusion
Time decay does not arrive as a sudden loss. It quietly works in the background every day an option moves closer to expiry.
For option buyers, understanding time decay in options is essential because the underlying asset must often move not only in the right direction but also quickly enough.
The next time you consider buying a Nifty, Bank Nifty or stock option, ask yourself one simple question:
“How much time does my trade need to work — and how much time is actually left?”
When you buy an option, you are not only taking a view on direction. You are also betting that the move will happen soon enough to outrun the clock.
Financial Risk Disclaimer
Options trading involves substantial risk and may result in the loss of the entire premium paid or significant trading capital. Past performance does not guarantee future results. The examples in this article are hypothetical and provided only for educational purposes. Investors should understand the risks, costs and characteristics of derivatives and consider their financial circumstances and risk tolerance before trading.