A simple monthly money framework that tells every rupee where to go—before it disappears.
If you often wonder where your salary went despite earning decently and paying bills on time, you are not alone. Most people stuck in a paycheque-to-paycheque loop are not careless spenders. The real issue is usually the lack of a clear money system, not a lack of income.
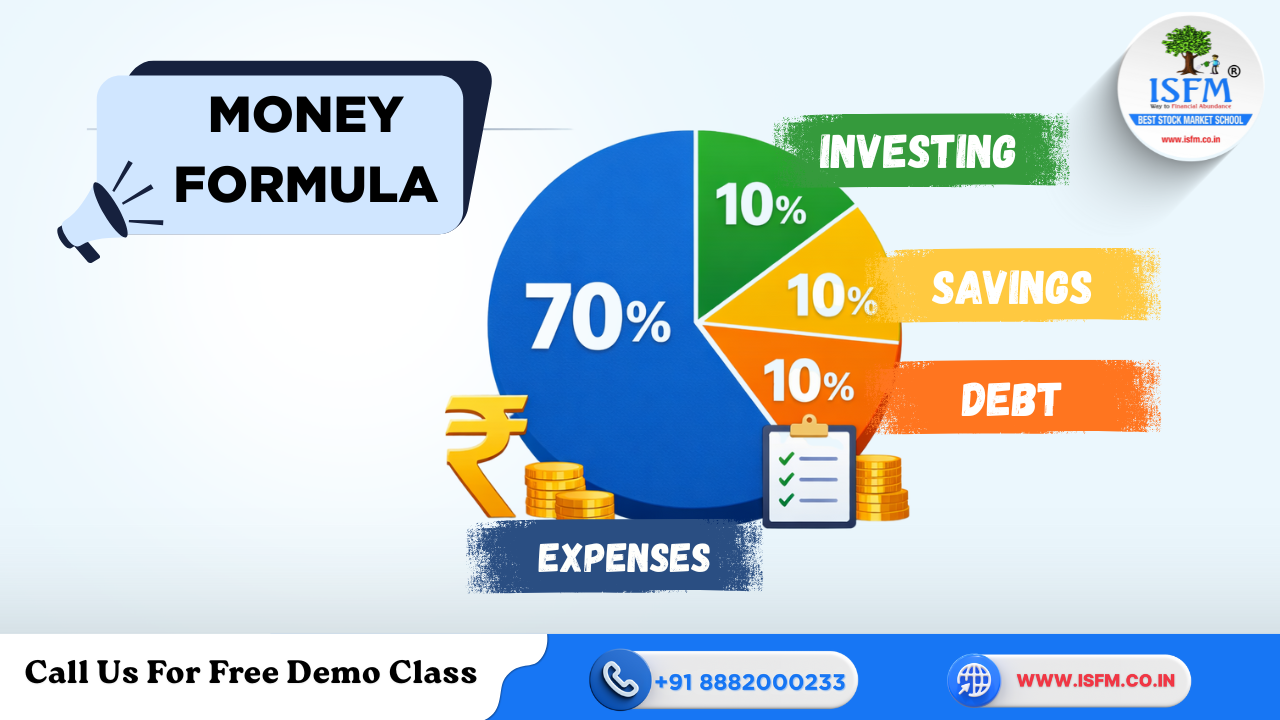
This is where the 70/10/10/10 budgeting formula helps. It is not a strict rulebook or a quick fix. Instead, it provides simple guardrails that make everyday financial decisions easier and more intentional.
What Is the 70/10/10/10 Formula?
The idea is to divide your monthly take-home income into four defined buckets, each with a specific purpose.
1. 70% for Living Expenses
This covers your current lifestyle:
- Rent or home loan EMI
- Groceries and utilities
- Transport and fuel
- Insurance premiums
- School or childcare expenses
- Day-to-day spending
This bucket supports how you live today.
2. 10% for Long-Term Investing
This portion is meant for wealth creation over the long run, not short-term gains. It may include:
- Equity mutual funds
- Retirement planning
- Systematic Investment Plans (SIPs)
You can explore how SIPs work here:
👉 SIP basics and long-term investing
https://isfm.co.in/stock-market-investment-course-in-gurgaon/
3. 10% for Short-Term Savings
Think of this as your financial shock absorber. This money is for:
- Emergency fund
- Medical or travel buffers
- Planned expenses like gadgets or repairs
Having a dedicated emergency fund can reduce dependence on credit cards or personal loans during unexpected situations.
👉 Why emergency funds matter
https://isfm.co.in/study-material/
4. 10% for Debt Repayment or Personal Growth
This bucket depends entirely on your current life stage. It can be used for:
- Paying off high-interest debt
- Skill development or certifications
- Education, therapy, or coaching that improves earning potential
Investing in skills often delivers returns beyond money.
Why This Formula Helps You Escape the Paycheque Trap
When income flows into one account and expenses come first, saving becomes optional. Optional savings rarely happen consistently.
The 70/10/10/10 approach flips this behaviour. It forces you to assign roles to your money before spending begins.
If your expenses exceed 70%, that is not failure—it is valuable feedback. It tells you whether:
- Your lifestyle has outpaced your income, or
- Your income needs to grow
Without a framework, this insight often remains invisible.
Over time:
- Long-term investing builds momentum
- Short-term savings reduce financial stress
- Debt dependence gradually falls
What If These Numbers Feel Unrealistic Right Now?
Most people cannot adopt this split overnight—and that is perfectly normal.
Start with one honest month of expense tracking. You may discover that:
- 85% goes into expenses
- 5% into savings
- The rest is unplanned
Then improve gradually:
- Shift 2–3% at a time
- Cancel one unused subscription
- Increase one SIP slightly
- Redirect bonuses or increments fully into savings
Consistency matters far more than perfection.
The Hidden Benefit Most People Miss
Beyond money, this formula reduces mental fatigue.
When your buckets are predefined:
- You know what you can spend guilt-free
- You know what should not be touched
- Small financial decisions stop draining your energy
This clarity often brings more peace than chasing higher returns or complex strategies.
Final Thought
Living paycheque to paycheque is rarely about willpower alone. It is about having a system that works even when motivation runs low.
The 70/10/10/10 formula may not be perfect, but it is simple, practical, and sustainable. For many people, it is the first real step toward regaining control of their money—and their peace of mind.