A company can report rising profits and still struggle to pay suppliers, employees, lenders, or investors. Why? Because profit and cash flow are not the same thing. Profit is an accounting measure, while cash flow shows the actual movement of cash into and out of a business.
For long-term investors, understanding this difference is an important part of fundamental analysis for beginners in India. This article is written by Sushil Alewa, SEBI Registered Research Analyst (INH100009433), to help investors understand how cash-flow analysis can support better investment decisions.
Strong cash generation can help a company repay debt, invest in growth, pay dividends and survive difficult periods. Investors should therefore look beyond reported profit. You can also read our guide on how to analyse a stock before investing for a broader fundamental-analysis framework.
What Is a Cash Flow Statement?
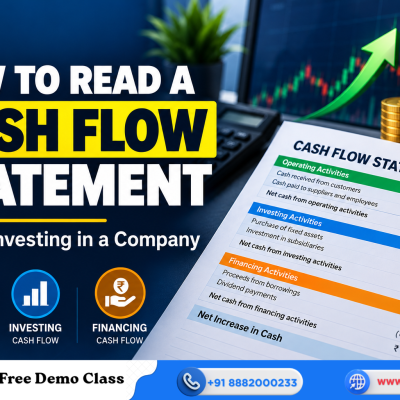
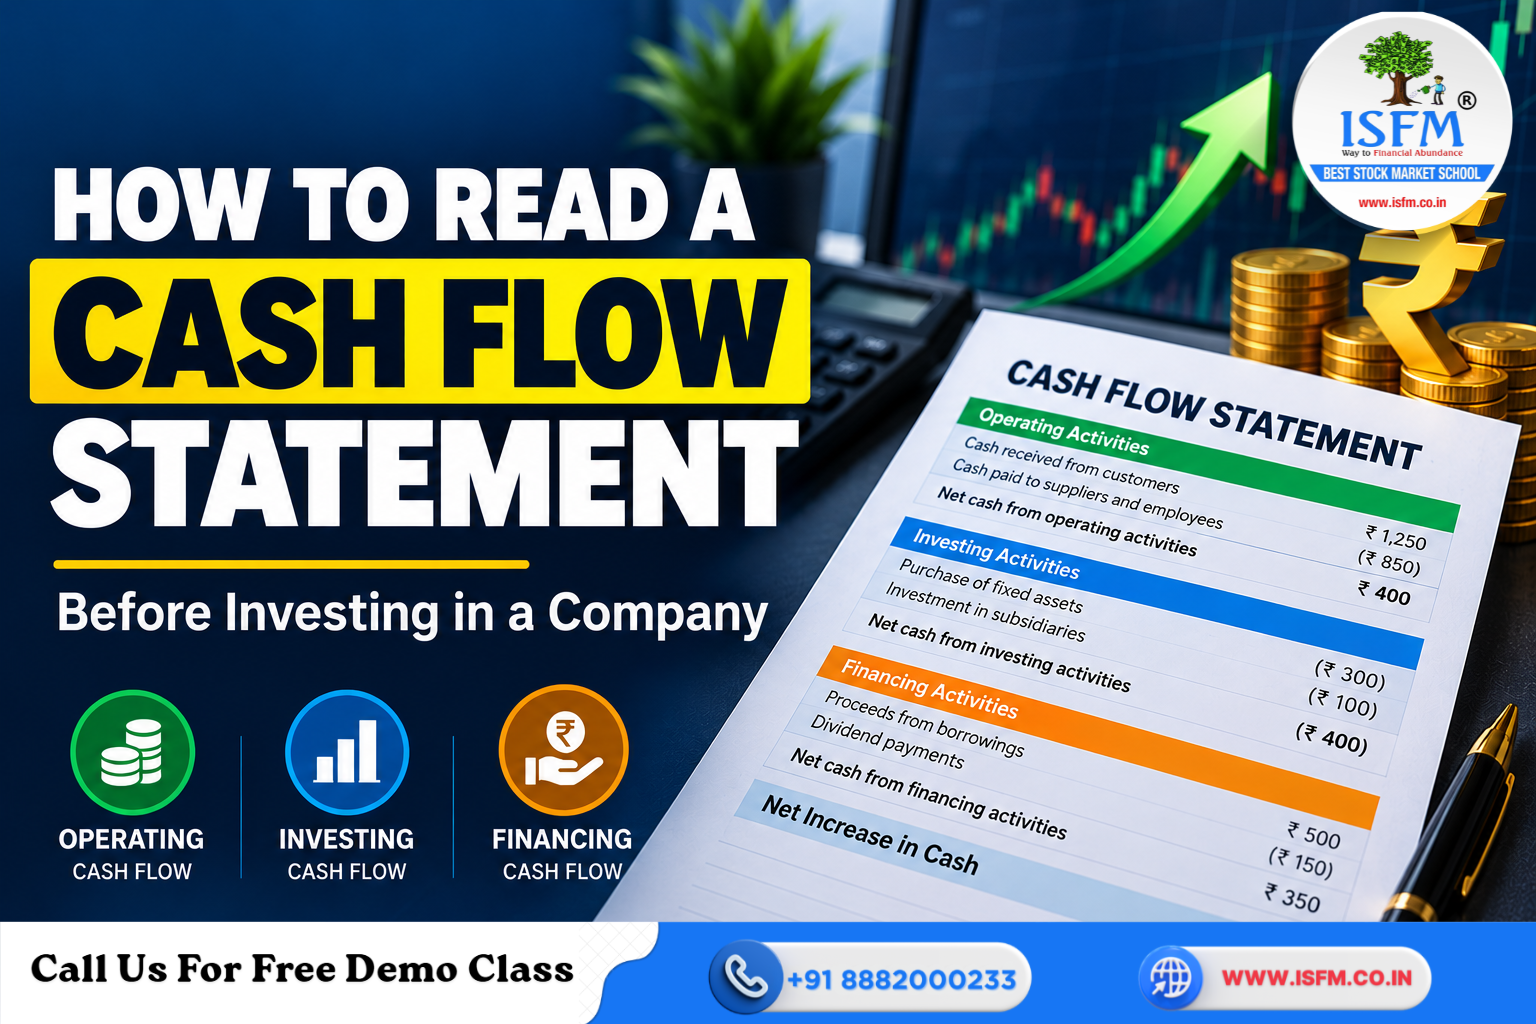
A cash flow statement records the movement of cash into and out of a company during a specific financial period. It has three major sections:
- Operating Activities
- Investing Activities
- Financing Activities
The statement helps explain changes in the company’s cash balance. However, it should be read along with the profit-and-loss statement, balance sheet, annual report and auditor’s notes.
Investors who want to develop a deeper understanding of company financial statements can explore ISFM’s Fundamental Analysis Course.
1. Cash Flow from Operating Activities
Operating cash flow (OCF) shows how much cash a company generates from its core business.
It includes cash collected from customers and payments to suppliers, employees, tax authorities and other operating expenses.
Consistently positive operating cash flow is generally a healthy sign.
Investors should compare:
- Operating cash flow with net profit.
- OCF over the past 3–5 years.
- OCF with revenue growth.
For example, if profits rise from ₹50 crore to ₹100 crore but operating cash flow remains around ₹20 crore, investors should investigate. Rising receivables, increasing inventory or working-capital requirements could be consuming cash.
2. Cash Flow from Investing Activities
Investing cash flow usually relates to long-term assets and investments.
Examples include buying machinery, building factories, investing in technology, acquiring businesses, or selling assets.
Negative investing cash flow is not necessarily bad. A company building a new factory may spend substantial cash today to create future growth.
Ask:
- Is the spending creating revenue or profit growth?
- Is the expansion efficient?
- Is capital expenditure funded by internal cash or debt?
- Are acquisitions generating acceptable returns?
3. Cash Flow from Financing Activities
Financing cash flow shows how a company raises and returns capital.
It includes new borrowings, debt repayment, share issuance, dividends and share buybacks.
Repeated borrowing to fund normal operations can be a warning sign. Frequent share issuance can also dilute existing shareholders.
Conversely, regular debt repayment and sustainable dividends can indicate stronger financial discipline.
Free Cash Flow: A Key Investor Measure
A popular measure in free cash flow analysis is:
Free Cash Flow = Operating Cash Flow − Capital Expenditure
FCF represents the cash remaining after capital expenditure. Strong free cash flow can help a company repay debt, pay dividends, buy back shares and fund expansion.
Investors should examine whether FCF remains consistently positive rather than focusing on one exceptional year.
Profit vs Cash Flow: A Simple Example
| Particulars | Company A | Company B |
| Net Profit | ₹100 crore | ₹80 crore |
| Operating Cash Flow | ₹20 crore | ₹90 crore |
Company A reports higher profit, but Company B generates more operating cash.
Company A may have significant credit sales where customers have not yet paid. Company B’s earnings may be better supported by actual cash collections.
This illustrates why operating cash flow vs net profit is an important check when evaluating earnings quality.
Useful Cash Flow Checks
Investors can calculate:
- Operating Cash Flow ÷ Net Profit — indicates how strongly profits are supported by cash.
- Free Cash Flow Margin = FCF ÷ Revenue — shows the proportion of revenue converted into free cash flow.
- Operating Cash Flow ÷ Total Debt — provides an indication of debt repayment capacity.
- Capital Expenditure ÷ Operating Cash Flow — shows how much operating cash is being reinvested.
There is no universal ideal ratio. Compare the company with its own history and similar businesses. For more financial metrics, see 10 financial ratios every investor must know before buying a stock.
Cash Flow Red Flags
Watch for:
- Rising profits but falling operating cash flow.
- Negative operating cash flow for several years.
- Receivables growing faster than revenue.
- Inventory increasing without matching sales growth.
- Continuous borrowing to fund operations.
- Large one-time asset-sale proceeds.
- Heavy share dilution.
- Dividends despite weak cash generation.
- Large unexplained profit-to-cash-flow differences.
One warning sign does not automatically make a company weak. Look for persistent patterns and read management’s explanations.
How to Analyse a Company in Five Steps
- Check the 3–5 year operating cash-flow trend.
- Compare operating cash flow with net profit.
- Review capital expenditure and investing cash flow.
- Study debt, dividends and share issuance.
- Read the annual report, auditor’s report and management discussion.
Investors can combine fundamental analysis with other market skills. Those interested in chart-based market analysis can explore ISFM’s Technical Analysis Course, while learners seeking broader market and regulatory knowledge can explore NISM Certification Training.
For readers looking for a broader professional understanding of equity markets, derivatives and financial-market concepts, ISFM’s Chartered Financial Market Expert (FMX) Course is another learning option.
Conclusion
Cash flow analysis helps investors distinguish between genuine business strength and accounting-driven profits. A positive cash flow statement does not guarantee a good investment, but persistent cash-flow weakness deserves attention.
Before investing, ask how much cash the company generates, where that cash goes, and whether the business can grow without constantly depending on lenders or new investors.