Uncategorized

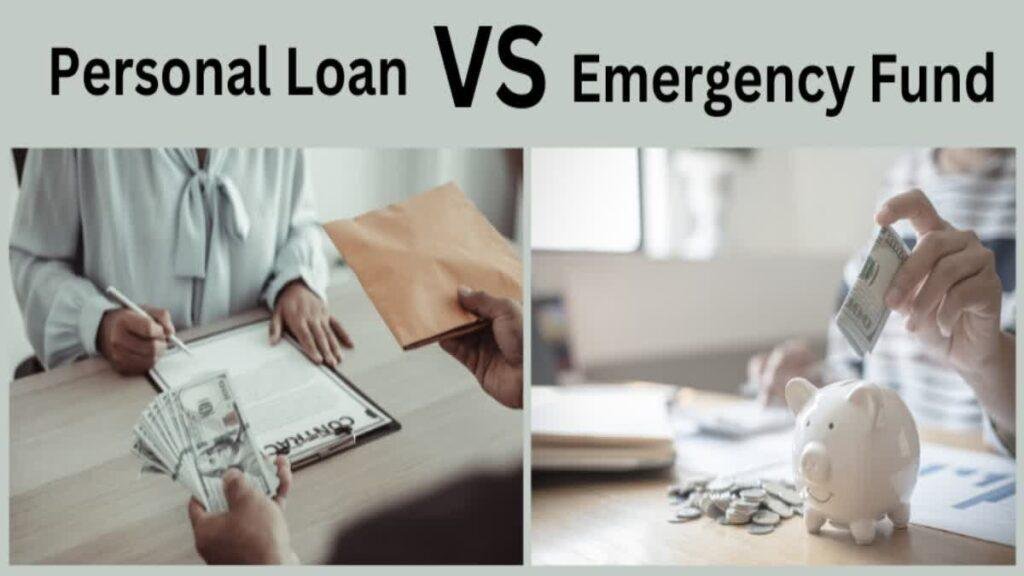
emergency fund vs personal loan
Uncategorized

Emergency Fund vs Personal Loan: What’s the Best Choice for Urgent Financial Needs?

Life is unpredictable, and financial emergencies can arise when you least expect them. Whether it’s a sudden medical bill, car repair, or job loss, having a plan for these situations is crucial. Two popular ways to address urgent financial needs are emergency funds vs personal loans. But which one is the smarter choice for you? Let’s dive into the details to help you decide. What is an Emergency Fund? An emergency fund is a reserve of money set aside specifically for unforeseen expenses. This fund is typically kept in a liquid account, such as a savings or money market account, allowing for quick access in times of need. Advantages of an Emergency Fund Drawbacks of an Emergency Fund Example: If your car breaks down, and the repair costs ₹20,000, you can withdraw this amount from your emergency fund without the stress of loan repayments. What is a Personal Loan? A personal loan is borrowed money that can be used for various purposes, including emergencies. These loans often require an application process, and if approved, the funds are transferred to your account. Advantages of a Personal Loan Drawbacks of a Personal Loan Example: If you face an unexpected medical bill of ₹50,000 but don’t have sufficient savings, a personal loan can cover the expense. However, you’ll need to pay interest over time. Also Read:A Golden Opportunity: Why Muthoot Finance Stands Out in the Gold Loan Industry Emergency Fund vs. Personal Loan: Key Comparisons When to Use an Emergency Fund? Pro Tip: Financial experts recommend building an emergency fund with 3–6 months’ worth of living expenses for maximum security. When to Opt for a Personal Loan? Pro Tip: Compare lenders to find the best interest rates and repayment terms before applying for a personal loan. Preparing for Future Financial Emergencies The Verdict: Emergency Fund or Personal Loan? Both options have their place in financial planning: The Ideal Strategy: Aim to build a robust emergency fund while staying informed about personal loan options. This dual approach ensures you’re prepared for any financial surprises without jeopardizing your future stability. By combining careful planning with smart financial habits, you can handle life’s challenges with confidence and ease.
Uncategorized

How to be Mutual Fund Agent? Why to be a Mutual Fund Agent?

What is the procedure to be a Mutual Fund Agent? What is commission structure in Mutual Fund industry? Mutual Fund market is growing at a high speed in India. Mutual fund industry was only 5 lakh crore in 2012 but now as on 2018 it is 23 lakh crore, approx. 500% growth is showing in our country. Indian investor are now understanding the things like putting money in to banks or insurance is not enough to cope up with the inflation. They need a product where there is no cap on upper side of the ROI. Everyone now a days want to invest in SIP if he/she have to understand of the money management or personal finance. Those who don’t have knowledge about it still now are investing in traditional products. Who is a Mutual Fund Agent : Mutual fund agent is a ARN (ALL India Mutual Fund Association – AMFI India) holder person who provide you platform to invest in SIP and other mode of investment in mutual fund. He will help you to complete your KYC and inform you available option in the market for investment. How to be a Mutual Fund Agent: You have to pass theNISM-Series-V-A: Mutual Fund Distributors Certification Examination. The certification is approved by the SEBI. You must have to score 50% to pass the certification during exam. It is a crash course you can book your seat anytime 15th days before taking the exam. Test will be online with MCQ questions. SEBI is the regulating authority of mutual fund in our country. SEBI has appointed NISM which is sister concern of the SEBI for investment education. Go through the link for online registration: http://www.nism.ac.in/certification/index.php/nism-certifications/mutual-fund/mutual-fund-distributors What is the commission structure? Mutual fund agent get twice commission which is very attractive model in the industry. Due to this only some wise people who were selling the insurance earlier now a days selling the mutual funds only. Types of the commission: So if you are able to collect the AUM 1 Crore then your trail income itself would be 10 lakh per annum and for this you no need to do anything again. Note: To pass the MF certification, get the Agent code you can contact to us or visit our office.

Scroll to Top
Get Free Demo Class in Live Market Trading
Be an Expert
Stock Trader

Just in One Month

16+

Years of Experience

30,000

Students Trained


Call Now