IV Crush Explained: Why Option Premiums Can Collapse After an Event?
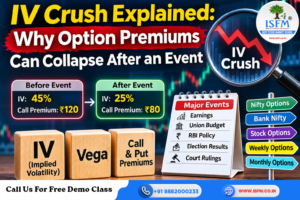
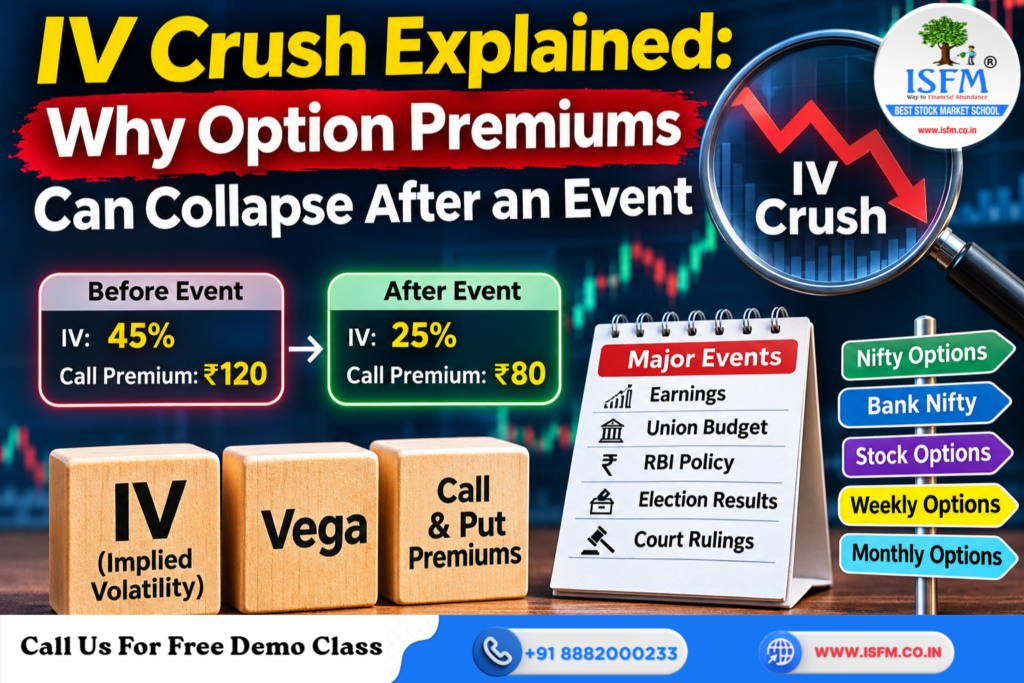
Imagine a trader buys a Call option before a company’s quarterly results. The stock rises 3% after the announcement, but the option premium falls from ₹120 to ₹80. The trader predicted the direction correctly, yet the trade resulted in a loss. What went wrong? The answer could be IV Crush, one of the most important concepts in options trading that beginners often overlook. Before major events, uncertainty can push implied volatility and option premiums higher. Once the event passes, this uncertainty may disappear, causing option premiums to decline sharply. Understanding this phenomenon can help traders make better decisions while trading Nifty, Bank Nifty, weekly options and stock options. According to Sushil Alewa, SEBI Registered Research Analyst (INH100009433), understanding implied volatility, option Greeks and changing market expectations is essential for evaluating options strategies. Traders should look beyond price direction and understand how volatility influences option premiums before entering a position. This article explains IV crush, the role of Vega and practical ways to manage volatility-related risks in options trading. 1. What Is Implied Volatility (IV)? Implied Volatility (IV) represents the market’s expectation of how much an underlying asset might move in the future. It is important to understand three things: However, IV does not indicate whether the market will move upward or downward. For example, before an important RBI policy announcement, traders may expect significant movement in Nifty. This uncertainty can increase IV, making both Call and Put options more expensive. Traders who want to understand price movements, market trends and volatility behaviour can strengthen their foundation through a structured Technical Analysis Course. 2. Why Does IV Increase Before Major Events? Financial markets react not only to actual developments but also to expectations about future events. Some events that can increase implied volatility include: Before such events, traders may purchase options to speculate on large movements or hedge their existing positions. As demand for protection and opportunities increases, option premiums may rise. Option sellers also demand higher premiums because they face uncertainty about the underlying asset’s potential movement. This combination can push implied volatility higher, particularly in short-term options. 3. What Is IV Crush? IV crush, also called volatility crush, refers to a sudden decline in implied volatility after a major anticipated event. Consider how the process works: This is why an option that looked attractive before an announcement can lose considerable value afterwards. However, IV crush is not guaranteed. Unexpected developments, continued uncertainty or fresh market information can keep volatility elevated. Understanding volatility is an important part of learning different option strategies, which is covered in detail in an Options Trading Course. 4. Vega: The Greek Behind IV Crush To understand IV crush, traders must understand Vega. Vega measures how much an option’s theoretical premium may change when implied volatility changes by one percentage point. For example: The approximate impact of Vega would be: ₹6 × (-5) = -₹30 Therefore, the option premium could decline by approximately ₹30 due to the IV change alone, assuming other factors remain constant. Remember, actual option prices also depend on the underlying price movement, time decay, strike price, liquidity and other market conditions. Learning Vega alongside Delta, Gamma, Theta and other option Greeks helps traders understand how different factors influence option pricing through an Advance Derivatives Course. 5. Why Can Option Buyers Lose Despite Predicting the Direction Correctly? Many beginners believe that buying a Call before a bullish event or a Put before a bearish event is enough to generate profits. Unfortunately, options trading does not work that simply. An option buyer must consider: An option buyer is not only betting on direction. They are also betting that the movement will be large enough to overcome the premium paid. A deeper understanding of option buying, option selling, strategies and risk management can help traders make more informed decisions through a Futures and Options Trading Course. 6. A Practical Earnings Example Consider a hypothetical stock trading at ₹1,000 before its quarterly results. A trader purchases a ₹1,020 Call option for ₹60. Before the announcement, the market expects approximately a 5% movement, and IV stands at 45%. After the results, the stock rises 3% to ₹1,030. The trader’s directional prediction was correct. However, the uncertainty surrounding the announcement disappears, and IV falls from 45% to 25%. Suppose the option premium declines from ₹60 to ₹45. Particulars Before Results After Results Stock Price ₹1,000 ₹1,030 Option Strike ₹1,020 ₹1,020 IV 45% 25% Option Premium ₹60 ₹45 The option buyer loses ₹15 per share despite the stock moving upward. The reason is that the underlying movement was not sufficient to compensate for the decline in volatility premium and other pricing effects. 7. Why Are Weekly Options More Vulnerable? IV crush can be particularly damaging to short-dated options because they have limited time until expiry. Weekly Nifty and Bank Nifty options can experience rapid premium changes around major announcements. At-the-money options and options with significant Vega exposure can also be affected. When an event passes, the uncertainty premium may disappear quickly. At the same time, time decay continues reducing the option’s value. This combination can create substantial pressure on option buyers. 8. How Should Traders Assess IV Before Entering? Before buying options around an important event, consider this checklist: Comparing expected movement with implied movement is particularly important when evaluating event-based option strategies. 9. How Can Traders Manage IV Crush Risk? Traders can consider several risk-management practices: Option sellers may benefit when IV declines, but selling options is not automatically profitable. Unexpected price movements, volatility expansion and inadequate risk management can result in substantial losses. Traders interested in systematic execution and rule-based strategies can also explore how automated systems evaluate market conditions through an Algo Trading Course. 10. Common Mistakes Traders Should Avoid Some frequently observed mistakes include: Avoiding these mistakes requires understanding option pricing rather than focusing only on market direction. Conclusion IV crush is not a mystery. It is the market removing the premium it had charged for uncertainty. For traders participating in Nifty, Bank Nifty,